Big Bank Brokerages Have Come a Long Way

September 14th, 2026 by Potato

For a long time, one of the big considerations of whether to build an index portfolio out of ETFs or mutual funds (in particular, TD’s e-series funds) was the cost of a trade: when nearly every broker around charged $10/trade, and you had to buy 4 ETFs to construct a canonical portfolio, that could be a few hundred dollars per year in commissions you’d rack up. For smaller portfolios, it just made more sense to go with the e-series.

Then Questrade changed the game with commission-free ETF purchases, and it became a more personal matter of the trade-offs between cost and complexity.

Now all-in-one ETFs have really cut down on the complexity involved. And even if you pay $10/trade, it’s not as meaningful if you’re only having to buy one thing. But the big bank brokerages have come a long way: while National Bank made all ETFs commission free, and BMO recently announced that starting today all trades will be commission-free, the others have all come out with a select list of ETFs that’s commission-free. And while the first few iterations of lists like that were a little less helpful, these days every single one includes a decent all-in-one option.

So the old advice of seeking out Questrade or Wealthsimple Trade or whatever isn’t really necessary. You can pick whatever brokerage you like, and you can find a very low-cost option to invest in. You choice may be constrained by their menu… but that may also help with the analysis paralysis. In alphabetical order:

  • BMO: all ETFs (and stocks) are commission free
  • CIBC: the list is here, and includes all-in-one funds from a mix of providers (VEQT, XGRO, XBAL, XCNS and VCNS)
  • National Bank: all ETFs are commission free
  • RBC: the list is here (have to click “see full list” on that page), and includes all-in-one funds from iShares/Blackrock (XEQT, XGRO, XBAL, XCNS)
  • Scotia: the list is here, and includes all-in-one funds from a mix of providers (VEQT, XGRO, XBAL, XCNS)
  • TD: the list is here, and includes all-in-one funds from Vanguard (VEQT, VGRO, VBAL, VCNS)

Of course, Questrade (or whatever) work perfectly fine as well (and we have to give Questrade brownie points for being the only brokerage able to figure out FHSAs before 2023 ended). But if you want the minor convenience of having your brokerage at the same place as your other banking, then commissions aren’t really a barrier to that any more.

The RRSP Home Buyer’s Plan

August 12th, 2026 by Potato

The RRSP is the most misunderstood tax shelter in Canada. It holds pre-tax money, which is not intuitive to think about at all. So when it comes to the Home Buyer’s Plan (HBP), there’s similarly a lot of conflicting articles out there that don’t quite analyze the options right.

First off, what is it? The Home Buyer’s Plan is a relief valve for RRSP investments, and an incentive for first-time home buyers: a first-time buyer can take up to $60,000 out of their RRSP when buying a house (presumably for the down payment but the funds can be used for anything — moving costs, furniture, renovations, just sticking in your savings account, the key test is that you bought a home, not specifically which dollar did which job). That relief valve means that people who aren’t sure if they should be saving for retirement or for a first house can utilize their RRSP for saving/investing, and still get a decent chunk of the money back out later if they end up buying a place. Then if you do take the money out of the RRSP, you have to put it back in over the course of 15 years, with a little delay (2 years) before you have to start. If you fail to make the repayments, the amount gets added to your income and you lose the RRSP room, just as though you had made an RRSP withdrawal in the year you skipped the repayment.

The FHSA is hands-down better in every way, but has limited contribution room, so a new buyer will likely have both a FHSA as well as some RRSP contributions made. And fortunately, you can use both.

Now if you’re cutting it close on having the funds for a downpayment, the HBP is a nice little incentive: because it’s pre-tax money, with a bit of planning ahead (you have to have had the funds in your RRSP for at least 90 days), you can take your downpayment savings, throw it in an RRSP, get your tax refund, then use both the original after-tax amount and the refund for a downpayment.

What if you don’t need that tax refund/pre-tax aspect to get more scraped together for your downpayment? That’s where it gets tricky: you’ll find articles describing the HBP as “an interest-free loan to yourself” (ignoring the opportunity cost of investing in your RRSP), or “like earning your mortgage rate in your RRSP”, which actually sounds worse than leaving it in and investing in equities. You may also see some comments saying if you don’t need it, don’t bother: if you’re going to have investments left over, wouldn’t you rather have investments in your tax shelter than out of it? And it’s never clear if these are the correct framings, or if someone is forgetting about the pre-tax nature of RRSPs, or just saying things to fill the silence.

So, let’s set up the analysis: you’ve been renting and investing the difference for over a decade, so have plenty saved up to put down on the house. If you don’t need that pre-tax boost to meet your desired down payment, does it make sense to use the HBP anyway? You need to figure out where to source the last $60,000 of downpayment (or land transfer tax, or pre-move-in-renos, whatever): from your non-registered, TFSA, or RRSP? Let’s put $60,000 (nominal) in each, and see how things work out for a simple model.

From our asset location breakthrough we should recall: the RRSP holds pre-tax money, so $60,000 coming from there is equivalent to less being taken from a non-registered or TFSA account. We should see this fall out when we calculate out the impacts. So this should work out best by taking advantage of the HBP. But that HBP also comes with a pesky repayment requirement and up-front paperwork and sitting on hold with your brokerage. Will it be worth the hassle and brainsweat?

Here are our three scenarios: take from the non-registered account; take from the TFSA; take from the RRSP-HBP. In each case, we’ll have 1/15th of the withdrawn amount ($4000) each year as cashflow to put into the account that was used (ignoring the grace period). In our tax shelters, our investments will increase at 6%. In our non-registered account, the tax rate will be 15% (i.e., a 30% tax bracket but with investments taxed at half the rate), for a 5.1% after-tax growth rate. In our RRSP, at the end of 15 years we’ll withdraw it and pay tax at 30% to get everything in after-tax dollars. I put everything in a Google sheet so you can follow along (no it’s not publicly editable — download a copy for yourself if you want to play with your own numbers).

1: Use the RRSP HBP

We pull the $60,000 out of the RRSP. The $60k in each of the non-registered and TFSAs keep growing. After 15 years, we have: The TFSA amount grew to $143,793. The non-reg, thanks to tax drag, grew to a just $126,530. The RRSP growth and slow rebuild over 15 years led to $93,104 pre-tax, but melting that down to make everything in after-tax dollars leaves us with $65,173. In total, the net worth at the end was $335,496.

2: Use the non-registered account

We use $60,000 of non-registered funds, leaving our tax shelters alone. The RRSP and TFSA each grow to $143,793 nominal (as the TFSA did before, good sanity check), but after melting down the RRSP was $100,655 after tax. Meanwhile the non-registered grew to $86,967. That leaves the total net worth for this case at $331,416.

3: Use the TFSA

Come on, you knew this was going to be the worst option — that logic of “if you have investments left over, wouldn’t you want them to be sheltered” is much more straightforward here. The re-built TFSA is worth just $93,104 at the end, with the other accounts that’s a final net worth of just $320,289.

Conclusion:

The HBP is useful for people who don’t have enough funds available for their downpayment: they can use pre-tax money for a little boost. Even if you do have enough, using pre-tax money and letting your after-tax non-registered investments grow does have an advantage: with fairly reasonable assumptions, about $4080 of future (i.e. 16 years from now) value — at that same rate of return, about $1850 of present day value. Now that is nothing to sneeze at, but for someone in the harried stress of buying a house, is that worth the headache of all the HBP paperwork and then repayment schedule? (Actually, yeah, it’s not that much work and not often you can get almost two grand just from tax optimization).

The (future) value of the HBP changes a bit as the assumed rate of return and tax rate change.
Rate of return 4%: $2885 and Tax rate 50%: $5101
Rate of return 5%: $3525 and Tax rate 50%: $6392
Rate of return 6%: $4080 and Tax rate 50%: $7636
Rate of return 7%: $4511 and Tax rate 50%: $8796
Rate of return 8%: $4774 and Tax rate 50%: $9829

But it’s always enough that the headache is likely worth it.

Not modelled: what happens if your tax rate changes over time.

Bonus:

What if you don’t invest in equities, and instead your non-registered is in bonds/GICs at your full tax rate? Then the HBP actually works against you: the tax drag on your non-registered account is too much for the pre-tax bonus of pulling the RRSP funds out to overcome, and you’re better off not using the HBP. So if you’re not going to invest the money (or use it on the house), don’t do it!
A Different Take on the FHSA

April 13th, 2022 by Potato

Budget 2022 proposes to introduce the Tax-Free First Home Savings Account that would give prospective first-time home buyers the ability to save up to $40,000. Like an RRSP, contributions would be tax-deductible, and withdrawals to purchase a first home—including investment income— would be non-taxable, like a TFSA. Tax-free in, tax-free out.

The new Tax-Free First Home Savings Account (FHSA) is pitched as a way to save up for your first home. It’s like a super-charged RRSP: you get to put pre-tax money in, and in one specific circumstance (buying a home), you can take it out tax-free. And if you don’t buy, you can roll it into an RRIF like a regular RRSP.

There’s lots to nit-pick with this idea: the $40k lifetime limit doesn’t make it much more effective for saving for a home than the old HBP option did. And while this is even better as you don’t have to pay it back and get to keep that tax savings, that’s a benefit you only see in later years vs the HBP — the $35k HBP was already letting you put that much pre-tax money to work for the purchase itself. On top of that, the $8k yearly limit means it will take 5 years to max out (and 4 to match what you could do in 90 days with the HBP and a regular RRSP). So at least it will push demand out if some people want to max it out before buying.

It’s a bit regressive, in that people in the highest tax brackets will see the biggest advantage from using the FHSA.

However, ignore all of the talk about using it for a downpayment. The fact that they took out the age limit and let you roll it into an RRIF mean that the FHSA serves another purpose: it helps renters shelter more investment income, functioning basically as more (and with an embedded option!) RRSP room. Someone who buys a place gets any increase in equity as a tax-free gain thanks to the principal residence exemption. That’s been a huge windfall in recent years, and can push people toward buying in an environment where prices are going up double-digits every year. That tax advantage also makes it even harder for those who don’t own to keep up. Someone can choose to rent instead and save the difference in monthly cashflows, but may soon run out of TFSA and RRSP room. An extra $8k/yr will help them shelter more of those gains.

And of course, provide that option to take the whole FHSA out at some point in the future to buy, tax-free.

Imagine a world where the cap and 15-year lifespan were removed and renters continued to get $8k/yr in room until they bought or turned 71 (and rolled it into a RRIF). Someone renting in a big, unaffordable city like Toronto could prioritize their FHSA, knowing that it would make it that much more possible to eventually buy when their indentured servitude in the city was over. $8k/yr at a 5% return would leave someone with nearly $400k after 25 years*. You could make a solid plan to do your time, renting happily along the way, and know that you could — tax-free — have nearly enough to buy a place in the boonies outright when your commuting days were done. Or, have more in your RRSP to support the costs of lifelong renting in retirement if you stayed in the city.

So while I don’t think this was a necessary thing to create (indeed it adds more complication to our tax and savings account system, and yet another financial literacy hurdle), and don’t think it’s going to do a damned thing for housing affordability… I welcome the FHSA. For many people, it will be the obvious first account to fill (even edging out a TFSA for those who plan to buy eventually). However, to be truly great and to help incentivize more people to rent and invest the difference and keep open the option to buy in the future, they’ll have to remove the fairly low lifetime contribution cap.

Indeed, I’m not sure many brokerages will bother to offer registered accounts that can only ever accept $40k, and are only available to the subset of renters who save money to invest — see how few bother to offer RDSPs.

* – remember that this is a hypothetical where they remove the cap and time limit. As it stands, the 2022 Federal Budget proposes a $40k lifetime cap and a 15 year maximum term to either buy a home or roll it into a RRSP/RRIF.

Investing Apps: Just Say No

January 26th, 2022 by Potato

Perhaps Commissions Aren’t So Bad

Dan Ariely talks about the difference between free and nearly free. Nearly free and free have basically the same effect on your overall net wealth: whether you pay 14 cents in ECN fees every month or zero as you accumulate your investments is going to have no measurable impact on your ability to retire. But the difference between a few cents and free on your trading behaviour is huge — people will trade a lot more when it’s free. Plus the sales commission on the selling side for Questrade is good for investor behaviour: not high enough to actually be a real barrier to selling, but puts just that little bit of psychological stop in before selling and prevents dabbling in day-trading.

So I’m worried these days that so many people don’t ask “what’s a good brokerage to use?” but “which investing app should I use? Is Robinhood in Canada?”

And as much as lower fees are better, perhaps there’s a behavioural benefit to paying a little bit of commission and we shouldn’t encourage zero-fee platforms. Plus these companies make money somehow, which may include providing worse fills (though that doesn’t seem to be allowed in Canada).

Smartphone Addiction

Your smartphone is an ingenious device, carrying more power than the desktop computer I had in university, and able to carry out many very useful functions. It’s no wonder many of us have them practically welded to us. But they are an insidious thing: they short-circuit our brains in some of the worst ways.

Paying by mobile phone reduces the pain of paying even beyond that of using a credit card, so it’s all too easy to impulse buy something and not even notice how much you spent with that tap. And so many apps are addictive (sometimes purposefully so) that just touching your mobile phone short-circuits all of your careful reasoning faculties. [only a modest exaggeration on my part]

Do. Not. Trade. On. Your. Phone.

Investing Apps

Long before there was daytrading involved, WealthSimple bragged about how a third of their users checked in with the app daily. Daily! For a robo-advisor. There’s nothing to do! The whole point is to have a long-term investment plan that you don’t have to babysit!

From their point of view it was great: more mindshare, better odds that someone is checking on their phone and a friend goes “oh hey what’s that.” So of course they loved it. But I was horrified. Setting aside the unhealthy relationship people had with their phone and this app, it was setting investors up for loss-aversion disappointment (or panic): the more often you check in on your portfolio, the more likely you are to catch a downturn and see that you’ve lost some money.

So mobile phone investing apps had a horrifying relationship to engagement and addiction before they threw day-trading into the mix.

Do. Not. Trade. On. Your. Phone.

Dark Patterns, Advertising, and Active Investing

The trailblazer in no-commission app-based trading, the brand that has become synonymous with the product itself, is Robinhood in the US. And Robinhood has been criticized for its dark patterns, gamifying parts of the user experience to encourage people to trade more often and make more speculative bets. For example, they’d flash digital confetti up on the screen as a kind of reward/congratulations for placing a trade, and list trendy stocks.

Now WSTrade looks to be copying some (but thankfully nowhere near all) parts of the playbook, with a mobile-only [update: mobile-first, as I took forever to publish this and got scooped in some ways and they now have a desktop web version] app, offering zero commissions and fractional shares. And they’ll give you a free stock, to really drive home that idea of trading individual stocks, with a lottery-like component (will your sign-up bonus be a penny stock or a really valuable share?).

They also moved beyond stocks into an even more speculative space with crypto trading. And while not a dark pattern within the app itself, their ads are highlighting all the new speculative investments you can trade with them (rather than focusing on the good parts, like that you can do long-term investing in an all-in-one ETF with no commissions — in fact I can’t say that I’ve seen a single ad along those lines).

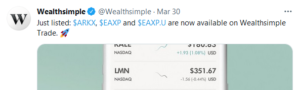
Screengrab of a WSTrade ad on Twitter highlighting the recent highly speculative securities you can now trade. I'll snark for posterity that anyone that bought ARKK is down 35 percent since.

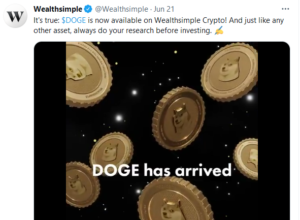
Screengrab of a WSTrade ad on Twitter highlighting the recent highly speculative securities you can now trade, including a crypto coin that was explicitly created as a joke. I'll add some snark that this highly speculative thing is down 50 percent since being added to the platform, and indeed has never traded above that point.

In the US case at least, there are plenty of stories of people getting caught in things they don’t understand and losing lots of money — whether through mistakes, or through functionally a fully enabled gambling addiction. Thankfully, here in Canada investing apps don’t push users toward derivatives to add risk on top of daytrading, though they are moving toward “instant deposits” to wipe out any chance for cooling off periods and do include crypto. And the “first stock” promotion of “up to $4,500!” reinforces the gambling aspect of investing, and fractional share ownership promotes speculating in individual securities long before a user is ready for that.

And that’s not to mention fat-finger trades — how many typos have you made texting on that device?

Do. Not. Trade. On. Your. Phone.

Academic Research Backs Me Up

Two recent papers back up my instinctive refrain that you should not be trading on your phone.

First, Does Gamified Trading Stimulate Risk Taking? looks at the gamification aspect:

“We find that gamification “nudges” participants to take on more risk, particularly when trading high-volatility assets. The effect is stronger for inexperienced traders with lower financial literacy.”

You can read a more lay-friendly version here.

Their finding on the moderating influence of financial literacy gives me some hope. However, it also worries me, as people with low financial literacy are the ones now searching for “investing apps” rather than “best brokerage” – the term brokerage is almost entirely missing from new discussions on Reddit, for example, so the people using these apps are much more likely to be the low-finlit ones most susceptible to the gamification, gambling, ads, and dark patterns.

Next, Smart(Phone) Investing? A within Investor-Time Analysis of New Technologies and Trading Behavior looks at people’s behaviour when trading on their phone.

“we find that smartphones increase the purchase of riskier, lottery-type, non-diversifying assets, and of past winners and losers. […] following the launch of smartphone apps, investors are—if anything—more likely to purchase risky, lottery-type, and non-diversifying assets as well as chase winners and losers on non-smartphone platforms. […] We find evidence against investors offsetting these trades on other platforms and against digital nudges mechanically driving our results. Smartphone effects are neither transitory nor innocuous: assets purchased via smartphones deliver lower Sharpe ratios. Our findings caution against the indiscriminate use of smartphones as the key technology to increase access to financial markets.” [emphasis mine]

That reinforces my more instinctive view that even touching your phone short-circuits your self control thought: simply trading on your phone increases the likelihood of buying riskier things, and it infects your trading even off your phone. They also include a reference to another study on purchases, supporting the idea that smartphones reinforce system 1 thinking, where people ordered more unhealthy food on their mobile devices.

Conclusion

If you’re looking to start investing, do not look for a zero-commission “app”. Start by reading, and then open a brokerage account and only use your desktop/laptop to trade. Even if the brokerage you ultimately choose has a mobile app, don’t use it, as even occasional usage may change your appetite for lottery-like stocks. Controlling costs is important and a virtue, but zero costs changes our behaviour in ways that may be counter-productive. A few dollars here and there (or even $10 big bank commissions) are not going to derail your long-term plan, but may keep you from trading more than necessary. And finally:

Do. Not. Trade. On. Your. Phone.

Reboot Your Portfolio Review

January 24th, 2022 by Potato

I wasn’t sure how I would react to Reboot Your Portfolio: 9 Steps to Successful Investing with ETFs by Dan Bortolotti after his announcement post, which said “What was needed, I recognized, was a step-by-step guide to designing, building, and maintaining a portfolio of ETFs over the long-term.” My Dude, I thought, that book already exists and it is called the Value of Simple.

But that’s the reaction of someone who spent too long in Science, where you have to cite prior work and it’s hard to publish replication studies. In art there’s all kinds of room for cover songs, and RYP actually has a really nice harmony with VoS.

Preaching to the Choir

RYP fully assumes that this is not your first book on investing, and so doesn’t spend much time on the basics like “what’s a stock?”. It dives right into “stop trying to beat the market!” Which I suppose fits very well with the title: you must first have a portfolio to reboot it.

Dan clearly and convincingly makes the case for why you shouldn’t try to beat the market, and why indexing (and specifically market cap weighted indexes) are the way to go. There’s a good section on factor/smart beta and why he doesn’t go for it.

He also has much more on building your plan before you invest, and how that influences your choice of investments and your ability to stick with them. Importantly, the planning section includes some key questions you should ask yourself as you’re building your plan.

RYP includes much more detail on how ETFs are built and the alternatives (e.g. smart beta), currency implications, etc. The book spends a bit of time digging into tracking error and transaction costs: the more advanced stuff that VoS doesn’t touch — again, a great complement. He also addresses head-on the common misconception about ETFs that track similar indexes having different prices: one is not “cheaper” or “a better value” just because the price per unit is lower. The price per unit is fairly arbitrary.

He also has a section on cutting ties with your advisor, to prepare you for the common arguments they might make. One addition I like a lot is his point that “You don’t need to change each other’s minds.” “There’s no point engaging in an argument with an advisor you’re planning to fire. He or she may be using fear tactics to encourage you to stay, which is unprofessional and provides another reason for you to cut ties.”

Then he has guidelines for how to buy your ETFs. He doesn’t go into quite the screenshot-level detail of VoS (which will also save him from having to release a new edition every 3 years — smart compromise), but hits all the main generalizable points, including using limit orders and rounding down your number of units.

Nitpicks

It wouldn’t be a BbtP review without nitpicking, but I have basically none. {gasps from the crowd}

The one thing that got me was my own bugbear (which is admittedly being pedantic on one page): in the TFSA-vs-RRSP bit, his RRSP description is missing the pre-tax nature of RRSP contributions. You should not pick an RRSP over a TFSA because it gives you a tax refund — you should be re-investing that refund anyway (or getting it back after grossing up or whatever). Yet Dan says “And if your income is significantly higher–once you’re in the six figures, you’re being taxed at more than 43%–then prioritizing the RRSP is almost a no-brainer, because that tax deduction is so valuable.” [Emphasis mine] This is the thinking that gets people to not add more to their RRSP to account for that gross-up/pre-tax bit, and then complain when they hit retirement that they have to pay tax on their RRIF withdrawals.

If you’re in a high tax bracket the RRSP is usually the better choice because there’s a higher chance you’ll be in a lower tax bracket later. The current tax deduction has nothing to do with it. If you have say $5k to save today and are debating between putting $5k in your TFSA or RRSP, putting $5k in your RRSP and enjoying a tax refund means you’ve really only saved $2850 — you had to contribute $8.77k to your RRSP [at that 43% tax rate] to have an equivalent situation to $5k in your TFSA (and then your tax deduction just brought you back to the same state as the TFSA, it was not valuable on its own).

I will note that he got it right immediately before that: “if you were in the same tax bracket for your whole life, the TFSA and RRSP would be essentially the same… an RRSP is particularly useful if you make contributions when your tax rate is high, and then make withdrawals when it’s low.” And to be fair, that this is something tonnes of otherwise careful experts get wrong (sometimes on purpose — people are irrationally motivated by tax returns, so selling them on saving and investing in their RRSP to get one works to get them to save and invest something much more so than a long, carefully worded explanation about pre-tax amounts — investing the same amount in a TFSA may be better, but that’s not always the counterfactual).

So Which One Should I Get?

As much as I have a conflict of interest, get both Reboot Your Portfolio and The Value of Simple. The lessons are important and it’s good to reinforce it, and now you’ll get it from two different voices from different angles to really help drive it home.

VoS is very purposefully designed for people who are not (yet!) DIY investors. It’s main criticisms have been that it is too simple, which I eat up. So if you’ve never made a trade on your own before (or are shopping for a friend or relative in that situation), I would suggest that you start with VoS, and then read RYP to reinforce the take-home messages of indexing and the value of all-in-one funds, and get those extra details on why you should pick certain index funds.

If you are already an investor, and are confused by all the different strategies out there (growth? dividends? crypto? meme… stonks?) then get RYP. VoS has more detail on what happens next for beginners (how do you read a statement, what are taxes and what do I have to do) if you’re confused on that after reading RYP, but if you’ve already opened a brokerage account and know how to use it, and are mostly stuck on convincing yourself to go with a simple index ETF route, BYP will probably be better at convincing you of that and will likely be all you need.