Directory of Fee-Only Planners and Coaches

August 17th, 2015 by Potato

I’ve talked about fee-for-service planners before, and how I think it’s how the financial advice industry should evolve — it’s a model that removes many conflicts of interest from the relationship, and maximizes transparency. I’ve even said that as a heuristic for finding an advisor it’s not a bad one, especially as at this point only a few have opted to go down that road.

So it was great when MoneySense created a directory of fee-only planners. ‎I linked to it a lot, it’s included in the book as a valuable resource, and lots of other people liked having it available, too.

They’ve now scrapped the list and are starting something new where they will not just provide a list of planners and what some might see as implicit approval, but also give them ‎an explicit seal of approval. The new process involves a hefty application fee, which will help pay for the magazine to do a survey of past clients, but will mean many fee-only planners will not choose to pay for inclusion so the list will be less inclusive. $2500 is a big fee for a directory listing, so the MS version of the directory is likely to become substantially smaller, and likely skewed towards the most expensive advisors.

I think there’s a lot of value in a free and open directory of fee-only planners.

So I’m going to create my own directory of fee-for-service planners. This will be a more buyer-beware type of directory. It will have no seal of approval, and use free tools and a minimum of volunteer effort (so forgive the barebones look). The only requirement for an advisor to get listed is to fill in the intake survey and have the appropriate business model (i.e. primarily fee-for-service). Those caveats out of the way, I think it will also be hugely useful to the community and capture a lot more planners and coaches than a closed directory with a high entry fee.

The directory is a simple Google Docs spreadsheet and there is also a sidebar link for the directory that more plainly introduces it than this post — please link to that version of the post and directory.

The intake form for advisors/planners/coaches to use is here.

Caveats: the important caveat is that this is meant to be an open listing and these are not recommendations. I don’t have the resources to vet any of these listings. I’ve mentioned a few more on the permalink.

Through the rest of this week I will start contacting the advisors that I know of to start filling out the form and adding themselves, so expect the directory to be a bit barren for the first little bit.

Thanks, and I hope you all find it helpful!

Canadian Personal Finance Book Guide

July 26th, 2015 by Potato

As much as I love blogs, if you’re coming to a topic for the first time and need a orientation and structure it’s hard to beat a good book. However, there are so many out there covering so many aspects of personal finance that it’s hard to know where to begin — especially as a Canadian, where suggestions from across the border can be hard to translate into practice here.

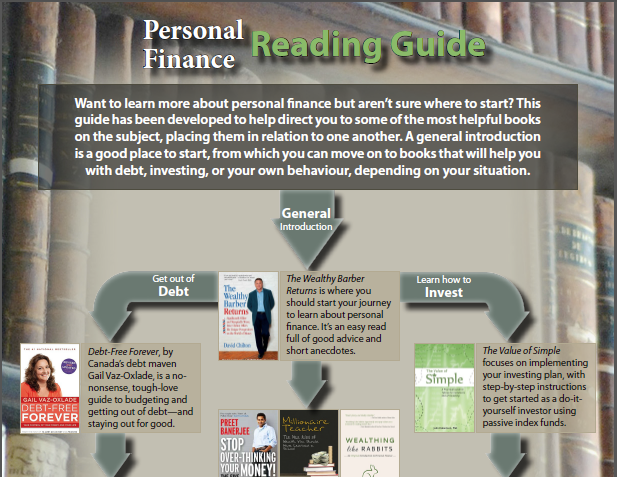
I’ve put together a reading guide to help people decide what Canadian personal finance books to read, which is a question I find myself answering a lot. I think something general and easy to read is a good place to start for nearly anyone. In fact, I recommend a few books designed to be general introductions — despite re-treading over some common ground, each brings a bit of a different view and adds information. That helps set the stage for the other books to follow, whether you need more help conquering debt and a budget, want to start investing, or just learning more about how to be a smarter consumer. A reading guide like this can also help put things in context: it’s hard to jump right in to investing and how to manage your retirement nest egg if you haven’t yet given any thought to the notion of saving for the future.

Personal finance reading guide -- click for PDF.

The reading pathway is a PDF infographic type document — click the image above or this link to download it.

I did reach out to a few others for their opinions on what to include for people starting out, but I’ve read a lot on the topic and used my judgement to create the pathway: the final curation, summaries, and opinions are all my own.

Disclaimers: I am the author of The Value of Simple, one of the entries in the pathway. I also embedded links to each book for convenience, and did use my Amazon affiliate code in those links. This did not affect my choice of books for the pathway.

Please feel free to share/mirror the PDF — the attribution is built in.

2014 Active Investing Update: Execution Risk

July 6th, 2015 by Potato

2014 was a busy, busy year. I wrote and released a book, in addition to all the other stuff going on in my life like being a dad, holding down a full-time job, taking on freelance/coaching clients, etc.1 So I did not have much time left for active investing, and that was one factor in putting in a rather shoddy under-performance of 8.6% vs my benchmark of a 50/50 mix of the Canadian and S&P500 e-series funds which pulled in almost double: 16.7%. Indeed, looking back through my notes from the year, active investing was almost entirely jettisoned from my life when the time crunch got bad. I spent almost as much time doing the bookkeeping and getting ready for tax season for my active portfolio in April as I did on researching new ideas or carefully following the ones I owned through the entire rest of the year. I did not listen to a single conference call all year. For over half of 2014 the time I invested on the active portfolio was precisely zero.

So this gets down to execution risk, another great reason to love simple index investing methods. Even if I did have a workable strategy to beat the index, and the smarts and emotional fortitude to follow through, there are still lots of ways to muck it all up (like not really doing it at all and leaving things on autopilot). That’s an added risk to active investing that we don’t talk about much, and a difficult one to accept: it’s all too easy to say something like “oh, if I had spent more time on it, I would have done better.” But the fact is that I didn’t, and I put myself into a situation where I could under-perform (and also granting that I may have underperformed no matter how much time I put in) by choosing to invest actively. It wasn’t a down year — I still made decent money, which may make it all the easier to fool myself if I wasn’t comparing to a benchmark.

I was overweight oil-related stocks, which hurt this year, but Canexus is a big stand-out mistake. It was a large part of my portfolio (a big part of out-performance in past years), and I just sat on it while it fell 55% in 2014 (and continued to decline in 2015). It’s stunning just how much value was destroyed by their attempt to build an oil-by-rail transloading terminal: over $350M invested, and it sold this year for $75M. Looking back (with the benefit of knowing that there were more declines to come), I should have seen the writing on the wall closer to mid-2014 that this supposed side project was threatening the stable, cash-generating chemicals business that I liked in the first place. That would have been a loss for the year, but not a loss on the position — instead I completely ignored what was happening and lost a lot of money by the time I woke up to how bad things had gotten this year.

I’ve been cutting down the number of positions I hold in the active portfolio and putting more and more towards the passive portfolio, but have not yet gone fully passive — at this rate it will take me several years to wind down to that point. Especially given that I wrote a book on how passive investing works and is so easy to do I should probably just liquidate the active portfolio and go fully passive. As I was putting this post together, Regal (RLC) received a take-over offer, which helps offset some of the other idiot moves I’ve made. The proceeds from selling that have been rolled into the passive portfolio. I also took that opportunity to do a big re-balance: I’ve had a mix of TD e-series and ETFs for a while now, in part because the e-series are easier to buy on autopilot, or in small pieces as the market dips (an idiosyncratic move purely for psychological comfort). I’ve now liquidated the e-series and rolled everything into just four ETFs — and I’ll note for new readers that my passive portfolio is in my TFSA and RRSP so there were no tax consequences to this roll-over, but doing the same thing in a non-registered account would have made me realize (and pay tax on) any capital gains the e-series funds had accumulated. It’s likely I will once again build up some e-series through the next year or two and do another shuffle to roll them into ETFs, or I might finally get into the habit of buying an ETF every few months for the passive portfolio.

This is two years in a row now of under-performance. My cumulative out-performance (“alpha”) is still positive, and by enough still that it raises an interesting conundrum, related to the previous posts on freelancing: in 2014 and the first half of 2015, I’ve ignored managing my active portfolio for the sure thing of freelance work (and the not-so-sure thing of the book). However, if I was able to maintain the 5-year average of out-performance from the years where I was working at it (which conveniently ignores this, my second-worst year relatively speaking), my time would actually be better spent doing investing research than editing/writing/coaching work. Of course, if I were to “risk adjust” that, then I’m back to taking the sure thing of working for a living and indexing my investments.

1. For that matter 2015 has been pretty hectic too, which is why this update on performance is coming 6 months after the fact.
Link to 2013’s update.

The Bad Idea That Wouldn’t Die

June 14th, 2015 by Potato

I keep thinking that there are a lot of people who really want or need a course on personal finance and investing, and there aren’t many resources for it. There are books of course, but some people just aren’t book learners, or prefer a course for one reason or another. There are some good continuing education courses offered through UofT and a few other universities across the country, but for most people who don’t live close to campus they’re out of luck. So I’ve thought about putting together a full online course on the matter, and while few people think it’s needed, when I actually asked who would sign up for such a beast the response was under-whelming.

A full course would be something like 12-16 hours of lectures and discussions, which would take hundreds of hours to prepare, practice, and coordinate. It’s madness to put in that kind of work before knowing for sure that there’s actually an audience at the other end. So it’s a bad idea. No one wants it, at least not online.

And yet it’s an idea that won’t die. I’ve kept thinking about how to put it together, how to change and add to the content of the book for a course, and moreover talking myself into thinking that it is needed and maybe the reason for the previous response is that people just don’t want to raise their hands over vague hypothetical options (also, the people who would want a course are likely not on r/PFC or here, excusing the underwhelming response earlier). So I’ve doodled a bit and come up with a preliminary syllabus for such a course.

But it’s still a terrible idea that’s going to take way too much time that I don’t have. Fortunately I’ve heard that Ellen Roseman plans to take one of her UofT courses online next year, and Bridget of Money After Graduation is putting together an online course on investing too. So maybe I can bow out and let them solve the problem.

Here is the preliminary course outline/syllabus, make of it what you will. Maybe it will get you excited and you’ll want to enroll or back a kickstarter-type thing to make it happen. Maybe Ellen and/or Bridgette will liberally borrow for their courses (and the outline is not the hard part of creating a new course so I don’t really mind). Maybe you will tell me that my outline is bad and that I should feel bad.

Planning, Investing, and Other Grown-up Money Concerns
Proposed Course Outline (each unit approx. 45 minutes + time for questions)

  • 1. Introduction and Money 101 Review
    a. What you should already know and have mastered.
    b. Budgeting and living within your means.
    c. Saving saving saving
    d. Emergency funds (insurance?)
    e. Credit cards, lattes, etc., etc.
    f. Clever parables, Diderot’s housecoat, Chilton’s four most dangerous words.
    g. Reading list to kick-start the course.
  • 2. Free Your Mind and Your Ass Will Follow
    a. The importance of attitude, behaviour, and long-term thinking.
    b. Neat grey matter tricks, including why free makes us stupid.
    c. Social animals and keeping up with the Joneses.
    d. Heuristics and rules-of-thumb (or should this be a whole other class?).
    e. Points-of-view.
    f. On uncertainty, and why a scientist is talking right now.
  • 3. Canoeing Down the Spanish River: Goals, Direction, and Having Fun [w/ Sandi Martin]
    a. Sandi’s talk from TPL, expanded a bit.
  • 4. Needs, Wants, and Other Sundry Topics
    a. Some concepts, because I had to stick them somewhere (inflation, compound returns, how to read graphs, use a spreadsheet, probably some other stuff).
    b. Needs and wants, and creating your minimum plan and ideal plan.
    c. Other goals and things that will affect your planning.
    d. An aside on the industry, some ranting, why I push the do-it-yourself way.
    e. Sketching out a plan and how to get there.
  • 5. Finally, the One in Which He Talks About Investing
    a. Investments help us make our plans a reality.
    b. Types of investments.
    c. Investing in businesses.
    d. Lessons from active investing: intrinsic vs market value, and what it means for long-term investing in a world that survives the coming zombie apocalypse.
    e. Investing in bonds, real estate, commodities, and other stuff.
    f. History and setting reasonable expectations.
  • 6. The Quick and Dirty Yet Completely Convincing Explanation of Index Investing
    a. The importance of fees.
    b. For repetition sake, a discussion of how fees matter.
    c. What can be controlled and what cannot be.
    d. Active vs passive – theory and past results.
    e. The added benefit of simplicity.
    f. Other ways of investing, and what they entail.
    g. The importance of “I don’t know”.
  • 7. Risk, the Gom Jabbar, and the Unfortunate Gambling Analogy
    a. Risk in everything.
    b. Many definitions of risk, and blending of volatility and uncertainty with risk of lifestyle impairment.
    c. Risk on different timescales.
    d. Risk tolerance.
    e. Enduring a market-crash in real time and Dune’s Gom Jabbar.
  • 8. Let’s Do It: Asset Allocation and Your Plan
    a. The canonical portfolio.
    b. How to decide on an allocation that will work for you.
    i. The age-based rule-of-thumb, and the completely arbitrary equity split.
    ii. The classic 60/40 one-size-fits-all portfolio.
    c. Apocrypha.
  • 9. How You Actually Do This: Three and a Half Investing Options
    a. Robo-advisors.
    b. Tangerine.
    c. TD e-series.
    d. ETFs.
  • 10. How You Actually Do This: Taxes and Tax-Shelters
    a. TFSA.
    b. RRSP.
    c. RESP.
    d. RDSP.
    e. Non-registered: taxes, dividend tax credit, capital gains, ACB.
  • 11. How You Actually Do This: Writing Stuff Down and Making Spreadsheets (Or Whatever)
    a. Condensing your goals and direction down into a written plan.
    b. Writing down your asset allocation and a rebalancing plan.
    c. Tracking stuff with spreadsheets (or pieces of paper in a binder, or whatever works for you).
    d. Tools that already exist and can help.
  • 12. Where I Talk About Processes and Take a Break to Riff
    a. Processes, lessons from engineering and health care.
    b. Good enough solutions.
    c. Execution risk, and some more talk about the behaviour gap.
    d. Some slack time to review any material from the previous classes that needs further discussion.
  • 13. Au Secours, Au Secours!
    a. When to get help.
    b. How to find help.
    c. Getting value-for-money.
    d. What an advisor/coach can do, and what they can’t do.
  • 14. The One Where I Reveal My Thoughts on Real Estate and You All Hate Me for It.
    a. The biggest purchase – and biggest expense – in your life, and why it deserves more thought than it gets.
    b. Rent vs buy analysis, and busting myths about renting. The ball pit analogy.
    c. Income suites are not magical.
    d. The housing bubble, and the pernicious myth of the property ladder.
    e. A look back at US housing bubble and why it’s not really different here.
    f. Real estate as an investment, direct and REITs.
  • 15. The Hardest Problem in Personal Finance [hopefully w/ secret guest(s)]
    a. The options that open up as you near retirement (annuities).
    b. Government benefits in retirement, CPP.
    c. Sequence-of-returns risk, longevity risk.
    d. Sustainable withdrawal rate, and the various schemes to convert a pile of investments into lifetime income.
    e. Decumulation plans.
  • 16. An Hour for Questions, or Lacking Those, Delicious Discussions of Dirty Dealing
    a. Q&A.
    b. Why I hate market-linked GICs and their dirty advertising.
    c. TANSTAAFL in general, being skeptical.

Risk and the Gom Jabbar

May 21st, 2015 by Potato

This is an excerpt from my book The Value of Simple. It has been edited to stand alone as a post.

In the short term the market as a whole (or an index representing it) can go down 50% or more. As you give the market more and more time to work out the short-term fluctuations stocks become less risky1. For some history, there have been quite a number of market crashes where stocks declined. The worst was the 1929 crash that marked the beginning of the Great Depression. Stocks fell some 90% and took about 25 years to recover. But recover they did, and if you would allow yourself to mark that experience down as a one-off, never-to-be-repeated event, then the worst market crashes involve stocks declining by about 50% (including the recent 2008-2009 market crash). Though those events can be quite painful for investors at the time, they do pass and the markets go on to set new highs. If you held on after any given crash the prices recovered within a few years – that’s long enough that in your day-to-day life you’d wonder if the prices would ever recover, but short enough that it would happen soon enough to matter.

When deciding whether to invest in equities, and how much you can allocate to them, on top of your time horizon is the matter of risk tolerance: your ability to receive a statement from your financial institution showing that the value of your investments had been cut in half, and to not panic or lose sleep at night – or worse yet, log in to your account and sell all of your holdings out of fear or disgust. If you’re the type of person who would panic in the midst of prices falling, seeing everyone else selling and decide that you would join the pack, you would take a “paper loss” that might recover (and given the historical record, would in all likelihood do so) and transform it into a permanent loss. Better in that case to stick to safer investments right from the beginning. Better still though to separate emotions from your investing, and keep a coldly rational long-term perspective.

You need to sort out your risk tolerance in advance: the midst of a market panic and sell-off is not the time to discover your risk tolerance isn’t what you thought and to try to change your plan when it is most expensive to do so. Indeed, that is the time to pull out your planning binder and remind yourself of the long-term plan and what you decided you should do in a market downturn when you were in a calm and rational state.

Unfortunately, there isn’t much of a substitute for that real-world experience of living through a market crash. In Frank Herbert’s science fiction masterpiece Dune, a young Paul Atreides had to endure a test of his humanity called the Gom Jabbar, wherein a magical box simulated the experience of excruciating pain (but left no lasting tissue damage); he had to display the ability to withstand short-term pain and resist his animal instincts in the interest of his long-term future by holding his hand in the box and enduring it by sheer force of will. There are times I wish a similar test existed for investors to accurately gauge their risk tolerance before a market crash, a way to harmlessly experience the pain and roller-coaster of emotions that accompany living through a market crash. Instead you will just have to make the most honest assessment of yourself that you can, and attempt to prepare yourself for what may come — bearing in mind that years-long market crashes and corrections that look like blips on long-term stock charts really consist of day upon day of uncertainty and fear-mongering news reports.

When considering your ability to take risk remember that risk tolerance can also include things like your job or life situation: if you’re in a field that is very boom-and-bust, then you may not want to invest as much in stocks which can also be boom-and-bust-like, because you may find yourself unemployed at the same time that the investments you’ll need to live off of are selling for less. If you’re younger, you have more time to wait for a market recovery or adjust your savings plan than if you are close to retirement. The young can also be more certain of their continued ability to work and save, whereas when you get older your chance of having your investment timeline cut short by a chronic disease increase.

Risk tolerance also touches on your financial ability to suffer losses without destroying your life. If you have a large financial cushion or flexibility in your financial needs you may have a higher risk tolerance. For example, if you were planning on buying a car in four years that would generally be considered too short a time-frame to risk putting the money you have saved up in equities. Yet if you had the flexibility to buy a cheaper car if you did suffer a loss, or to delay your purchase by a few years, it might not be such a black-and-white situation as the timeline alone suggests.

Though I have attempted to put you into the proper mindset with all the warnings of the riskiness of stocks, the simple fact is that investing in stocks is the only easily accessible way to get such high expected returns, with so little effort and expertise required. The warnings are to prepare you for the inevitable rough ride in investing, and not to scare you off of investing entirely. Indeed, including at least some exposure to stocks is critical to reducing your overall risk of running out of money in retirement.

Keep in mind that the volatility of the stock market is very attention-grabbing; market crashes are stressful times and stories of hardship and loss can get passed down through the generations. However, the hidden risks of paying too much in fees or starting too late can be just as costly over the long run – and you cannot recover from those by waiting.

And though I would caution against trying to “time the market”, better returns come from buying when the market is low (remember the aphorism “buy low, sell high”). That will bring us to rebalancing later [in the book], but it’s important to remember that when you’re in the phase of your life when you’re saving money (i.e. when you’re young), you want to be buying stocks when they’re cheaper. So if (when) a market crash comes along, that’s not the time to wring your hands, lament your losses, and consider selling and getting out of the crazy world of investing. Instead it’s the time to cheer the bargains, to buy more, to take advantage of the temporary insanity of the traders to set yourself up for later. Market crashes, as much as they are feared and vilified in the media, usually end up being good for a young investor, and conversely, people do not make money by “waiting for things to settle down.” As long as you have faith that in the long term businesses will continue to be profitable and grow, then eventually your diversified investments should perform for you.

Understanding your risk tolerance in advance is critical for investing success and your ability to stick to your plan through future volatility. Risk tolerance has many components, including details of your situation as well as your psychology.
In the short term, equities can have large losses and high volatility. But history shows that patient investors have been well rewarded over the long term.

1. If you have a definition of risk that is not simply volatility.