Money 201 and a Crazy Idea

March 24th, 2015 by Potato

I have re-created the Money 201 session from our Toronto Public Library talk in February, and put it up on YouTube for your enjoyment and/or education and/or ridicule:

Now, here’s my crazy idea: wouldn’t it be great if there was a full online course along these lines? A full course would be about 12-24 hours of material, and would be designed to have some coherency and flow. So would you be interested in something like that? Doing something like that would take hundreds of hours of time to plan, draft, record, and upload: would you be willing to pay for it (either to pay for an online course with group hangout sessions/webinars, or to sponsor a video series through something like KickStarter)? If it was say $200 for an online course?

As cool as it sounds, it’s not like an online course is the only way to learn this stuff: there are plenty of books and blog posts, there are even some videos out there on individual components of personal finance/investing/planning if you look hard enough. But other than the odd book it’s very haphazard. If you’re coming in with no background, a blog is a terrible thing to encounter as the information is scattered all over chronologically, and often blog posts are focused on debating little technical issues which are not so helpful for a first-timer looking to learn.

There are in-person courses around: Ellen Roseman and Gail Bebee both offer courses on investing, with the added bonus of the reputational backing of the continuing education arms of UofT and Ryerson (at $245 for ~12 hours of class time). Plus there are plenty of free Toronto Public Library talks on the matter. Of course, you have to live in (or haul your butt to) Toronto for those classes, and I don’t think the rest of the country is as well supplied, so an internet option may be needed. So comment, email, or Tweet if you want to see something like this (especially if you would want to support it and make it happen).

Update: I am working on a course along these lines. I’ve streamlined the draft syllabus from what I linked to above, and am looking into using Thinkific to deliver the course. However, it’s a lot of work to get it right so expect many months yet (I don’t want to put a date to that after already blowing through one planned launch date).

I’ve started to give the idea some thought, and even thought about who I might pull in for guest lectures (some of whom are game if I can raise some money), but this is something that will only come together if there’s a real demand in the community for it — and the demand might be for someone other than me to do it. And just because I was crazy enough to think it was feasible doesn’t mean I’m the one who has to do it: if you think Ellen or someone else should make an online course then mention that in the comments too, and I’ll give them a poke.

“Have I told you about my latest crazy idea?”
“You have lots of crazy ideas, it’s hard to tell which one is the latest.”

Note: the self-publishing series will return at the end of the week.
On MERs and Past Performance (Again)

March 1st, 2015 by Potato

A reader writes in, asking about a particular mutual fund manager. They’ve read The Value of Simple, but aren’t sure if they should switch to DIY index investing considering their particular funds have outperformed net of fees the past few years, and have won Lipper and Morningstar awards.

This was an interesting email to receive. The reader had four different ways of saying that past performance for the particular fund was good.

The Lipper and Morningstar awards are basically useless as indicators of a fund’s ability to out-perform their fees in the future. The Lipper awards in particular are completely focused on past performance, so winning one doesn’t tell you anything a screen of past performance wouldn’t already. The Morningstar award includes “style consistency” and “tax efficiency” as other criteria, but is again basically just a metric of past performance.

There are studies that show that past performance is not a criteria for finding winning mutual funds, so by extension, the Morningstar and Lipper awards shouldn’t have any bearing, either. Indeed, I went back and spot-checked the 2010 Lipper winner, and they badly under-performed in the subsequent ~5 years. Their 10-year average (including the out-performance that won them the award and subsequent under-performance) is now equal to the index. I then quickly checked all the 3-year winners in the Canadian equity category from 2007-2014 (the range data is available from Lipper), and all but one of them went on to under-perform the index. (I didn’t check all of the winners in all categories because they have dozens and dozens of categories to try to spread the love around)

So why is past performance not a good indicator of future performance, when it is for say, job performance for an engineer or a sales associate? There’s always a combination of luck and skill in performance and outcomes, but the proportions change for different tasks. The engineer’s outcomes might be mostly skill and a bit of luck, so a good one in 2010 will probably still be good in 2015. A sales associate might have an equal mix of factors affecting their past performance — finding the skill may not be too hard, but it may not be immediately apparent in past results. But for mutual funds the skill can be completely swamped by luck, so it’s quite hard to find, especially from the customer’s chair.

I’m not dogmatic about indexing and active management, but pragmatic: I think some people can out-perform due to skill, maybe even enough to beat their fees if they do it professionally. However, identifying that small percentage of managers is a task that’s comparable in difficulty to just being an out-performing active investor yourself, and that is very difficult in my mind. You have to have a good understanding of what skill looks like to be able to spot it amongst all the luck and marketing. And the MER acts as a huge hurdle: these guys might be very skilled, but out-performing by even 2% every year is quite an achievement, and that would be needed just get you back to even. In my opinion, going with indexing is the better bet.

Another consideration is what value you get for the MER paid. A big issue in the industry is that typical big bank/big firm advisors just sell funds and don’t provide the detailed plans, hand-holding, tax advice, or other services they claim in newspaper articles are reasons to avoid DIY investing. If you’re getting good service, then you have to decide whether it’s worth 2% — or whatever the fee difference is — to keep getting that level of service, or if you’d rather do it yourself and save on the fees and avoid the risk of their performance streak ending. If you’re not getting good service for what you pay, then paying the higher MER is purely a bet on their ability to out-perform, and historically that has not been a good bet to take. Demand better service to get your money’s worth, or take matters into your own hands (which may include paying fee-for-service for the expertise you need to supplement your own efforts in indexing).

Value of Simple RRSP Series Part 3: Over-Contributions

February 17th, 2015 by Potato

Inspired by recent real-life events1, let’s talk about what happens if you accidentally over-contribute to your RRSP.

Unlike for the TFSA, the government does track your RRSP contributions closely and will update you each year. Good thing too — RRSP contribution room accumulation is a good deal more complicated than asking how old you are and looking at your own activity, like with the TFSA’s across-the-board $5500 per year. Simply check the bottom of your notice of assessment for your contribution room for the year.

Your financial services providers will send you receipts to summarize your RRSP contributions at the end of the year, which makes it easy to report these on your taxes (which you do have to do).

There are penalties for over-contributing, but you get $2000 of leeway, so if you over-contribute by just a little bit you can carry it forward to use in a future year, without a penalty. If you over-contribute by more than $2000 there will be penalties, and you’ll want to pull it back out as soon as possible — though on that last point most people don’t find out about their over-contribution mistakes until the next tax year (at tax time in the spring), by which time they’ve earned enough new room to absorb them, so withdrawing to stop accruing penalties is often not necessary in practice2.

When you do have an over-contribution, you can only claim a deduction up to your available room, but you have to report all of the contributions — the difference will get carried forward. Do not edit the amounts on your RRSP contribution receipts to keep your reported contribution below your deduction limit.

In most (all?) tax software, if you enter contributions above your deduction limit, the excess will automatically be carried forward, so you may not need the previous instructions for dealing with Schedule 7, but be sure to have a look at your Schedule 7 to be sure.

If you’ve over-contributed beyond the leeway room, then you’ll be facing a 1% tax per month — and this form (T1-OVP) is where you calculate and report it.


1. The sad thing is, there’s going to be more than one RL friend saying “hey, this one’s about me!”
2. Be sure to check your own situation and take care of over-contributions as soon as possible if you’re over the $2000 allowance.

Value of Simple RRSP Series Part 2a: When to Defer

February 16th, 2015 by Potato

In the last post we talked about how to defer your deduction, but glossed over when that would make sense. A reader pointed out that there are actually few1 cases where it makes sense to do so.

The base case is where you have some money and are in a low tax bracket now, but will be in a higher one soon. I had suggested that this was where it would make sense to contribute immediately but defer the deduction, so as to avoid ongoing taxation of the funds if you simply waited to contribute. But this reader encourages us to look at those cases more closely.

Let’s say your money grows at 5%, and you get taxed on half the growth (like capital gains), and you start in the 20% tax bracket, and move to the 35% bracket the next year. If you contribute $100 to your RRSP and hold off to take the deduction, then you’d have:
Start in RRSP: $100
Refund from taking deduction at 35% bracket: $35
Tax-free growth in RRSP over year: $5
Total: $105 in RRSP, $35 outside, total of $140

If you contribute and take the deduction immediately, you’d have:
Start in RRSP: $100, initial refund: $20. Put that in the RRSP, but then assume the refund from that comes the year after (at the 35% rate).
Total after the year: $126 in RRSP, $7 outside, total of $133.

If you wait to contribute, your $100 grows to $105, but then if you have to pay tax at 35% on half the growth (the gain is realized as you contribute) you’d only have $104.12 to contribute. But that extra contribution would bring you a slightly larger refund.
Total: $104.12 in RRSP, $36.44 outside, total of $141.14.

It’s tough to compare these outcomes because they’re not all in the same place — money in the RRSP is subject to taxes on withdrawal. So we can contribute a bit more to make the sheltered amount equal and the comparison easier: for the last scenario, $105 in RRSP, $35.88 outside by contributing $0.88 and getting $0.31 back. So, a slight benefit to just paying the taxes and contributing the larger amount when you’re in the higher tax bracket — which you’ll have to weigh against the need to track and report the non-registered investments for taxes.

This is all assuming that you have the contribution room to contribute more later. However, RRSP contribution room is finite, and can be quite limited if you’re in the situation of having lower employment income (e.g., a grad student on scholarship) and plenty of non-registered investments. RRSP contribution room carries forward, but it does not grow or get inflation adjustments. So in the case where you can only contribute $100 no matter which point in your life that is, would it make sense to contribute right away and then defer taking the deduction? Again, the comparison gets tricky because we’ll have different amounts inside and outside the RRSP, so it’s hard to compare head-to-head. If you figure that the RRSP is money good (you’ll be able to pull it out completely tax-free) then the contribute immediately and defer the deduction plan wins; it looks like the break-even is where the rate on RRSP withdrawals is the same on the rate applied to the non-registered investments.

Reality is a bit messier because you wouldn’t be immediately pulling the RRSP money out again, you’re hoping for it to keep compounding into the future. Using your room as soon as possible and deferring the contribution gets you more in the shelter, versus having more in your non-registered account to face the drag of taxes over time. I haven’t figured out the math to get an analytical formula, but from playing with a spreadsheet it does look like it does generally make sense to contribute and defer the deduction if your room is finite and your tax drag is about a quarter to a third of your marginal rate (which is the case, even for dividends, for people with incomes over ~$45k).

Ok, that was a bit confusing and not especially conclusive. There are cases where it makes sense to contribute and defer taking the deduction, mostly when your contribution room is limited (where you’ll end up with non-registered investments no matter what), but it’s not as hands-down beneficial as I thought when I did it as a grad student, and not as simple as I implied in the previous post looking only at the value of the deduction (and ignoring that the contribution will likely grow over time even if left in a taxable account). If you’re not worried about running out of RRSP room (with employment income without a pension adjustment, and with a TFSA, it’s hard to run out of tax shelter for many people), then the contribute-but-defer plan is likely not for you.

Still, the previous post on knowing how to defer is still useful because we don’t have perfect knowledge of the future. There are situations where you may contribute in a lower tax bracket and want to defer taking the deduction, and that’s when you contribute without knowing what your tax rate for the year will be in advance. For instance, if you make regular contributions in the first half of the year, but then find yourself unemployed in the last half, you may wish to defer taking the deduction for those contributions until you’re back up to speed; or where you work one job and make contributions but then get a big raise towards the end of the year or early in the next. Yes, it may have been even better to hold off on making the contributions in the first place, but that would have required an impossible ability to predict the future.

1. Actually the word used was “never”.

Value of Simple RRSP Series Part 2: Deferring the Deduction

February 14th, 2015 by Potato

Putting money into your tax-sheltered accounts (RRSP, TFSA) is great: not only are the gains on your investments not taxed, tracking the gains and distributions becomes totally optional because the CRA does it for you (or more properly doesn’t care, and treats it like a black box where only what goes in and comes out matters).

While using your TFSA right away can be a good move for almost everyone, the RRSP can be trickier: if you’re young and not making much now, you may want to wait until you are closer to your peak earnings (or at least a few tax brackets higher) before you start contributing and taking the deductions. You can of course hold on to your contribution room — it will carry forward until you’re ready to use it.

However, a neat feature is that the contribution and taking the deduction are separate steps: you can contribute to your RRSP to get tax-free compounding and a freedom from paperwork and hold on to the tax deduction until a higher-income year. I did this towards the end of grad school, maxing out my meager RRSP room while deferring the deduction until last year when I was working full time. Indeed, this is one of the classic examples of where such a move is the way to go. Another case where you may want to defer taking your deduction is when you have a new job or big raise that starts partway through the year, and won’t hit that next tax bracket until the year after.

When should you consider deferring the deduction? [edit: please see the next post for when deferring might make sense.] I don’t have a precise formula or spreadsheet ready for you. You do need to consider the time value of money: a tax deduction (refund) now will be more valuable than one a few years from now. There should be a reasonable chance of getting to a higher bracket soon — and the bigger the projected shift the more you may be willing to wait. Waiting 3-4 years to move from a 20% tax bracket to a 31% one was a no-brainer for me — the tax refund was worth 50% more in just a few years. Deferring for a decade in the hope you’ll move from 31% to 33% or 35% may not make sense for you. If you still have TFSA room, use that first — you can always pull from your TFSA to contribute to an RRSP later. But if your TFSA is full and you’re starting to build non-registered investments while you wait for your salary to increase to use your RRSP room, then contributing and deferring may make sense.

I’ll just note that some cases make sense for deferral (like mine in grad school), but for many people out there in the middle class, the climb through the tax brackets is gradual enough that it usually will not make sense to defer taking the deductions — if you’re not sure, you’re probably one of the many who will be just as well off taking the deduction immediately.

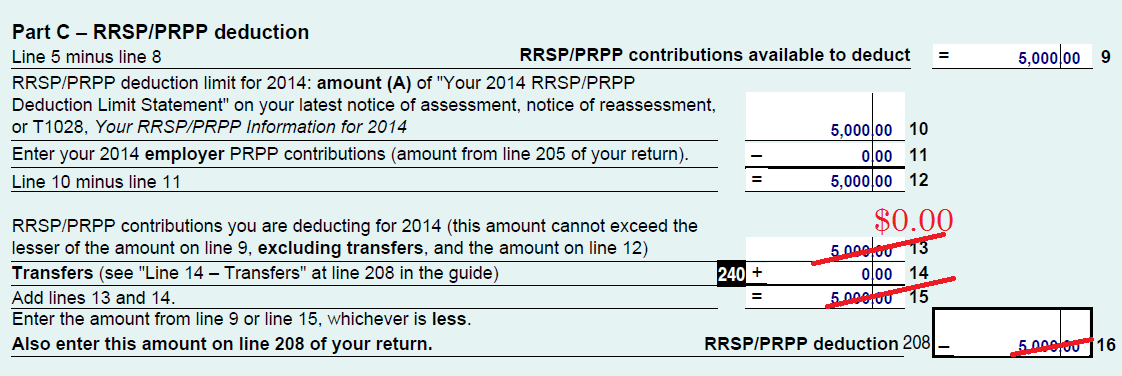
How do you engage in this magical deferral? The contribution step is the same as always: move money into your RRSP (and once it’s in there, invest in something). You’ll get a contribution receipt, which you will report on your taxes — even if you plan to defer taking the deduction you must report the contribution, and you must have enough RRSP contribution room for it. Your tax software will likely then try to automatically use all of your contributions for deductions right away to maximize your current refund. If instead you want to defer them, search for a form called Schedule 7. If you follow along in the PDF/paper version of the form, it’s divided into parts:

    Part A — Contributions
    Part B — Repayments under the HBP and the LLP
    Part C — RRSP/PRPP deduction
    Part D — RRSP/PRPP unused contributions available to carry forward

Part C is where the magic happens: you just tell the CRA how much of your contributions you want to use for a deduction this year. If you contributed $5000, but want to carry-forward that whole amount, just override line 13 with $0 (you want to use none now). Or you can enter a partial amount if you want to use some now and some later (useful if you’re just over a marginal tax bracket break).

An image of the CRA's Schedule 7 for deferring your RRSP contribution.

To do this in TurboTax, click on the forms button at the bottom of the screen, and then the “form lookup” option. Start typing “schedule 7” and you’ll see it pop up. Once you open it, it will look almost identical to the CRA form above. If you try to change line 13, it will take you to a special TurboTax “worksheet” where you can enter the amount you want to carry-forward, which saves you a step of subtraction. Note that you can also go directly to the worksheet from form lookup (just look for “RRSP”), but it makes more sense to me to look for schedule 7 than some special TurboTax thing.

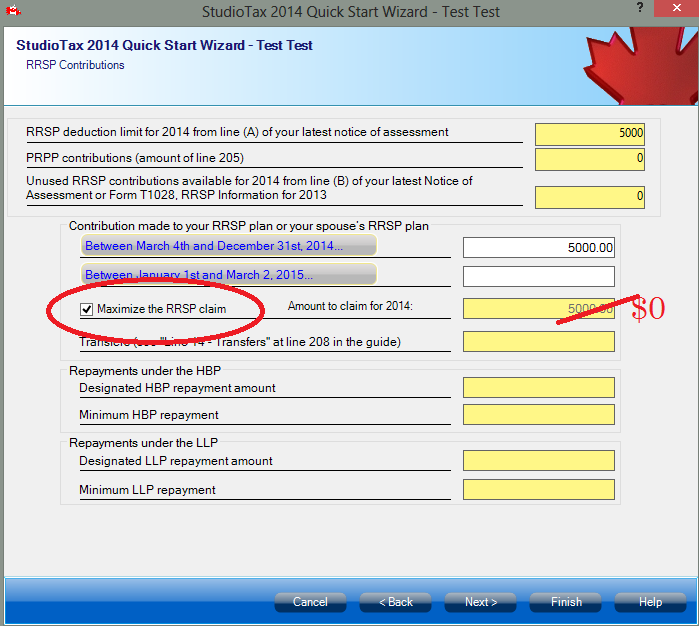
In StudioTax, you can adjust this right from the initial wizard when you’re entering your RRSP contribution information: uncheck the “maximize RRSP claim” option. I’m a little less familiar with Studiotax, but it appears that if you want to defer your deduction after you’re past this wizard step, you have to click on “forms” at the top to ensure Schedule 7 is in the “added forms” category, then click on “federal forms” at the bottom of the screen. Double-clicking on line 13 will bring the wizard screen below back up so you can adjust how much you want to claim this year.

An image of the CRA's Schedule 7 for deferring your RRSP contribution.

Once you’ve deferred your deduction, you’ll see it show up on your notice of assessment. If you use the same tax software year to year, it will pull that deferral forward for you next year; if not, you’ll have to enter it from your notice of assessment, and you’ll see it show up in the very first line of Schedule 7 as unused RRSP contributions. Every year your tax software will try to automatically use your deferred contributions and any new contributions for you, so if you’re trying to defer for more than a year then you’ll have to make the adjustment to line 13 each year until you’re ready to take it.