The Shopkeep Model of Investing

October 8th, 2014 by Potato

One of the challenges I think people have with investing is that the actual purchasing part is quite unlike other aspects of our daily lives. We use metaphors like “fruits and baskets”, describing different accounts (RRSP, TFSA, etc.) as baskets where you place investments (cash, stocks, bonds, funds thereof) — but you can’t go down to your local general store and ask the shopkeep for a half dozen index funds off the back shelf to stick in your basket.
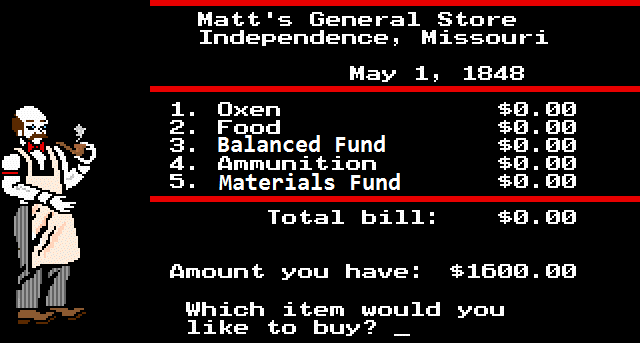
A shopkeep from Oregon Trail sells oxen and other goods to eager travellers, but not many mutual funds.

Even after you decide that you want to keep things simple and use a straightforward indexing approach, and you have to figured out what to buy to fit that plan, you have to figure out how to buy those investment products. The big barrier can come when you have to go and “buy an XIC.” There’s no counter you can walk up to and make that happen.

The investment industry is either full-service (with associated fees) or a completely do-it-yourself “wholesale/auction” experience. The high fees attached to many products are built in assuming that you will pay for planning, stock-picking, and other help even if you never get it and you’re only after someone to help you make the transaction. Many people are disappointed with the depth and quality of the advice they receive in a bank branch, and are surprised to find that the staff are in fact in a sales role. Whether satisfied with the advice or not (and in many cases one needs more background knowledge to know that they should be dissatisfied), I think many Canadians are shocked at the fees when put in context.

I think some Canadians do go into the bank not looking for advice, but for a shopkeep. So they’re not dissatisfied with advice because they never really expected any — they were just looking for help making a transaction. But again, the fees for that level of service are shocking.

I would have thought that with TD’s e-series there was enough of a MER there to let the branch staff help with placing orders — even if they were not allowed to spend time on e-series clients — but instead the e-series are completely off-limits to branch staff. There is no minimal-cost “purchase assistance” type service. The closest equivalent is Tangerine, which packages everything together for you so you just need to throw money at the account — it’s the closest implementation I’ve seen to how many people talk about “buying an RRSP.”

And that’s just mutual funds: with ETFs there are added levels of confusion for people expecting the shopkeep model. It is not at all like going in and picking up a cool book that your friend recommended from the shelf — it’s more like buying livestock at auction crossed with a old-time bazaar where everyone is selling everything to everyone else and the prices change by the second.

It would be interesting if someone could take a one-time commission (not an ongoing trailer fee forever and ever amen) to make that a more pleasant retail experience. Put up a list of prices that stay where you put them, and the shopkeep eats the fluctuations; or to make buying ETFs more like buying mutual funds where the division from the money you have to throw at the asset class happens automatically, and where no one gets burned by limit orders or the lack thereof. Getting back to reality, there’s no getting around having to learn this somewhat different (but once you get it, not difficult) way of purchasing investments.

Of course, to help people navigate on their own when there is no clerk to guide them is why I wrote The Value of Simple, and that implementation part forms the meaty middle of the book. Maybe one day more banks and fund companies will drop the pretense of offering high-cost advice and stock picking to every customer, and instead offer transaction assistance for low-cost index funds. Until that day comes, sign up below to receive updates on the book.
Announcing The Value of Simple

September 28th, 2014 by Potato

By now you all know that I’ve been working on an investing book. I’m pleased to announce that the title is The Value of Simple: A Practical Guide to Taking the Complexity Out of Investing.

I’m aiming for a December 1 release and I’m really excited about it. I’ve put a lot of work into refining the book and testing it out with readers (novices and experts) to make sure it works. I even like love the title.

Briefly, The Value of Simple: A Practical Guide to Taking the Complexity Out of Investing is a plain-language guide to implementing an index investing strategy for Canadians. With a focus on developing good processes to minimize the room for human error and step-by-step instructions, the book walks investors through the elements of managing their finances for the long term: how they can determine an appropriate asset allocation, devise a savings plan, stick to it through automation, track their investments, and deal with the inevitable issue of taxation. It provides tools and templates, along with default suggestions and rules-of-thumb to help prevent analysis paralysis and get investors started as soon as possible. Moreover, it directs the reader to focus on what can be controlled, to minimize effort and complexity.

For the average investor, a low-cost index investing approach is the easiest and simplest method available, and also provides the highest chances of long-term success. While there is a lot of material available on why investors should choose passive approaches over high-fee active mutual funds and what passive investing products exist, the average investor is at a loss on how to implement a passive index investing plan.

Investing doesn’t have to be complex to be successful. Indeed, simple solutions are valuable and are more likely to succeed in the long term. This book will guide you through implementing those simple solutions.

There is a separate webpage for the book (click here!) where you can find more details and pre-order it (and soon, purchase it). You can also sign up for email updates below (and I promise to only send a few):


We Have TFSAs Now: Lose the HBP

September 18th, 2014 by Potato

A little while ago Rob Carrick idly wondered on his facebook page/discussion group if the home buyer’s plan (HBP) was a good idea. In case you’re not aware, the HBP is one of the few ways you can take money out of your RRSP without paying tax on it: you can pull up to $25,000 out as a first-time buyer, and repay it over the next 15 years. The HBP primarily accomplishes two things.

1. It lets people contribute to their long-term (retirement) savings with an “out” to use those funds for a down payment on a house/condo. This way they can save for the future without having to plan what will be house funds and what will be retirement funds.

2. It lets people get a tax refund on their down payment that they can also use on the house right away, effectively borrowing from their future selves. In the short term, it’s an incentive to buy.

On top of this, it has a psychological effect: home ownership and post-secondary education are the only sanctioned reasons for borrowing from your RRSP. Add how irrational people can be about taxes and tax deductions, and it’s a bit of a sacred cow. In the right light (octarine?) it looks like the government encouraging buyers to reach for as much real estate as they can, using everything at their disposal (including their RRSP).

With TFSAs in place now though the first point is well taken care of by that tax shelter: you can easily throw all your long-term savings in there as a young person, and if you need to raid them for a down payment (or whatever) then you can, even in excess of $25,000. Plus it’s already set up to be indexed to inflation so we won’t have to worry about future whining that the HBP isn’t big enough. As for point two, I really don’t think we need any more tax incentives or holiness attached to housing, so doing away with the HBP in favour of encouraging TFSA use would suit my politics just fine.

To be fair, this may need a few years for transition, and would present a bit of a savings conundrum to people who get employer RRSP top-ups, but I find it hard to feel that’s a major flaw in my plan. Let’s simplify the RRSP that one extra step, and phase out the HBP.

Tater’s Takes: Tax Refunds Are Not Windfalls

September 11th, 2014 by Potato

I haven’t had a Tater’s Takes round-up post in approximately forever. Preamble: early summer was crazy at work, so it was good that I finished the draft of my book in the spring so it could sit with the editors over that time. Several people now have copies in their hot little hands and are providing great feedback so I can make one last round of polishing before I start getting proofs made up. I’m getting super excited for the book. I’ve put a tonne of effort into it (way, way more than I expected when I thought I’d just make a PSGtDIYI 2nd edition) and I think it’s shining through in the manuscripts. Most people who haven’t gone completely silent have praised the initial copies, particularly novices to finance (the target audience). There’s still almost two months to go before I run out the clock on the window to hear back from publishers, and at this point I almost want to get rejected because it’s just so close to being ready to go in the self-published route that it would hurt to have to pause to work out the details with a traditional publisher.

Blueberry is (as every proud daddy will say, I’m sure) uncanny smart sometimes. Like most toddlers, she has become attached to a blanket as her “lovie”. We’ve heard the horror stories of kids who lost their lovies or those that get disgusting because it’s hard to separate them long enough from the child to wash, and Wayfare planned in advance. We bought multiple copies of the blanket in question, and have kept them in rotation so there’s always a clean one ready and so that they all have the same degree of wear. These blankets are identical in every way, right down to their electrons sharing the same spin states. So we were caught completely off guard when Wayfare surreptitiously did the blankie swap for laundry and Blueberry instantly noticed and freaked out. How could she tell? How could she tell so quickly and decisively? Baby genius, that’s the only answer.

Ok, links.

First up is yours truly, scraping the bottom of the barrel for active investing ideas. I hardly post at all on that topic, and considering I’ve got a book on how easy index investing can be coming up it was best to shunt it to another venue. Nelson was kind enough to host this post on HNZ over at Financial Uproar.

I’ve just discovered Steve at Kapitalust. I’d suggest starting with this recent post on the intersection of ethics and investing.

Sandi’s back! Or semi-back, as someone else takes over half-way through.

Robb at B&E preaches about the inevitability of changes to embedded commissions for advisors in Canada.

Michael James has a new twist on comparing car salescritters to mutual fund salescritters and why embedded commissions make more sense for one than the other.

Oh, so this is public now.

Dan at OBFW reviews a new book (not mine, despite what you may think when you see the title — I’ll unveil the title of mine in just a few more weeks, be patient kids) and raises an interesting question: “Would you rather get a $1,000 windfall at age 27 when you are trying to scrape together a down payment for a house or a $1,300 windfall at age 70 when you have close to $1 million in savings?” in suggesting that young people use their RRSPs over TFSAs (and spend the refund).

I think that’s unfortunate framing. A tax refund on an RRSP contribution is not a “windfall” — it’s a deferral of a government obligation. Michael James puts it best when it calls it the government’s share of your RRSP. Of course the short answer is that if you really need the money to buy a car or pay down debt then you should just use the money for that rather than investing it and then redirecting a part back towards the more urgent need in a roundabout way that involves filing paperwork with a large government agency. But let’s do the math on this suggestion:

Let’s say you scrape together $1k to invest while you’re in the 20% tax bracket at 27, and expect to end up withdrawing in retirement at age 70 in the 31% tax bracket. We’ll use 6% real returns. If you suddenly realize, no, you need $200 of that back to pay down some debt you forgot about or to buy something shiny, then you could either put just $800 in your TFSA, or contribute $1k to your RRSP and spend the $200 refund.

If you just trusted your original decision to invest $1000 in your TFSA, you’d have $12.3k to spend in retirement. But to be more fair, the invest-$800-in-your-TFSA scenario would leave you with $9800 to spend at age 70. If you put the $1000 in your RRSP and got a $200 refund to spend on stuff then you’d only have $8453 to spend after the CRA took their cut in retirement. Spending the government’s share and mistaking the TFSA vs RRSP issue adds up to a much bigger deal than just $1000 when you’re young or $1300 when you need it less — you could spend the same “windfall” amount on whatever necessities you have when you’re young in that case, still use your TFSA, and come out way ahead.

If you only decided to spend the refund because it came months later and you were weak (and you didn’t get commiserate value from the dollars spent), then picking the RRSP over $1k in the TFSA would be like borrowing $200 from your future self and paying an interest rate of nearly 7%. But, maybe spending $200 now is more important than spending $3847 when you’re 70 and don’t need it. Of course that logic of “X now is more important than Y later” can lead to a lot of debt if you don’t put some reasonable limit on it.

Nelson also posted about why he prefers the RRSP to the TFSA. I left a weak, off-the-cuff comment about why I still like the TFSA. One other point that came to me when re-reading it is the issue of the refund timing: if you run the math, assuming you’ll be in the same tax bracket before and after retirement then the two shelters come out neck-and-neck in terms of outcomes. If you end up in a lower tax bracket the RRSP provides an advantage; higher and the TFSA will win out. However, the canonical comparison assumes you invest with pre-tax money and avoid withholding (or have the funds available to invest the refund in advance). In practice not only do people run the risk of squandering the refund, it also tends to come later, so the TFSA gets a tiny, miniscule head start on compounding (when looking at it from multiple decades in the future). Anyway, nitpicky.

Use RRSP with DB Pension?

September 9th, 2014 by Potato

Over on the twitter, people wondered whether to contribute to an RRSP if they have a defined benefit pension plan. The answer depends on a few factors, chief amongst them your expected tax rate in retirement versus your tax rate now (or in the near future if you choose to contribute now but defer the deduction for a while). Other factors can include your situation and plans — if there’s a decent chance you’ll need the money before retirement, it may be best to keep it in a non-registered account until you’re sure you can lock it up.

The short answer is easy though: most of the time an RRSP is better than investing in a non-registered account, even if you have a DB pension. You can think of it like this: you have a pension adjustment if you’re in a DB plan, so you likely only have a bit of RRSP room, with the rest being used by your pension. If you had no pension and lots of room, would you use all of it or only 80%? Maybe you’d be in a case where only using a bit made sense, but likely you’d use it all if you could.

Really the only clear case where you should not use your RRSP is if you expect to be on GIS in your old age (but in that case it’s not likely that you have a job that’s offering a DB pension).

The easy case is when your tax rate in your earning (and saving) years is higher or equal to your tax rate in retirement: the RRSP will make sense (assuming you invest the refund or would invest less if you were using a non-registered account). Indeed, if you do invest the refund the RRSP will beat out the TFSA in terms of returns for the case where your tax rate in your savings years is higher than in retirement.


The harder case is to construct a scenario where your tax rate in retirement is higher in retirement than in your working years. If you’re particularly high in the income spectrum then you could have OAS clawbacks, effectively a 15% surtax on retirement incomes over $71k — which if you’re using a typical DB replacement of 70% means you’d be making over $100k in your working years (over $115k in DB income — say $165k in your working years — and it won’t matter anyway). The most likely case for higher tax rates in retirement is the least predictable one: where your inflation-adjusted income stays the same, but the government of the future has raised tax rates. It’s an analysis paralysis black hole to try to worry about deviations too far from the present set of rules. You could be higher than you are today if you make a lot more later in your career, but then if you expect to move up a tax bracket or two you can still contribute to your RRSP and defer taking the deduction. Still, the answer is not as simple as “skip the RRSP if your tax rate in retirement is higher.”

Even if your tax rate will be higher later, the RRSP can still beat out a non-registered account by allowing for tax-free compounding and easing the record-keeping and reporting burden of investing. The tax-free compounding benefit doesn’t sound that spectacular, but bear in mind that after the first jump the marginal tax brackets in Canada increase fairly shallowly. For instance in Ontario the difference between earning $75k and $90k is only 6%, and that’s made up of a federal 4% jump and provincial 2% increase at similar but not quite identical break points, so you could be “higher” later but have an even smaller difference of maybe just 2%. Would tax-free compounding be worth that?

It’s tough to say because the drag from taxes is not precise, and you can defer some capital gains into retirement, but let’s estimate it: assume you have an 8% nominal return (note that taxes are on nominal returns rather than real returns). Assume that your employment marginal tax rate is 31%, and that through the magic of capital gains partial inclusion, the dividend tax credit, and handwaving, your tax burden on those gains is 12% per year (taking a rate below the half-way mark to try to assume some benefit of capital gains deferral). Then you could invest $10,000 after tax in a non-registered account, earn 8% nominally, and pay $96 in tax the first year, or put the $14,493 pre-tax* into an RRSP, and earn 8% tax-free. After 10 years you’d have $19,745 in your non-registered account versus $31,289 in your RRSP. The tax drag would mean that your tax rate could be as high as 37% after 10 years — 6% higher than our starting tax rate or a full federal + Ontario tax bracket move — and the RRSP would still roughly break even. As time wears on so does the non-registered tax drag — after 28 years in this example the tax-free compounding benefit would offset being hit with OAS clawbacks.

I’m not sure what the correct estimate of the non-registered tax drag would be, but in this example I’m neglecting any tax on deferred capital gains which would further improve the outcome for the RRSP case. I’d ballpark it as somewhere between 1/4 and 1/2 of your marginal tax rate, and likely closer to the high end of that.

So yes, there is a very good chance that investing in an RRSP will beat out investing in a non-registered account, even if you move up by a tax bracket over time or face OAS clawbacks.

Basically:

  • If you’re really low income, where you expect to get GIS in retirement, then avoid your RRSP. Invest in a TFSA, and if you manage to have more to invest than your TFSA contribution room, invest in a non-registered account.
  • If you’ll be in the same or a lower tax bracket in retirement, then definitely maximize your RRSP! Tax arbitrage FTW! Just remember to invest the refund too, where you can.
  • If you’ll be in a higher tax bracket then it may still be worth it:
  • If you’ll be just one bracket higher, it will quite likely work out better with an RRSP due to the non-registered tax drag.
  • If you’re in the OAS clawback range (expected retirement income of ~$71k-$115k in today’s dollars) then consider it carefully, but enough time and non-registered tax drag may still make it worthwhile.

I’ll finish by noting that my rule-of-thumb is simply “TFSA first”. For many the RRSP will come out mathematically optimal (note that the TFSA gets the same benefit of tax-free compounding discussed here), as many people can expect to end up in a lower average tax bracket in retirement. However, the TFSA is more flexible, better for lower-earning people, and moreover is easier to plan around with set contribution limits by year and no pension adjustments, and higher income people can usually find the funds to contribute to both. Mostly though it’s the gap between theory and practice that makes me push the TFSA: most people do not put pre-tax money in their RRSPs (or invest the refunds) — they invest what they have on hand at the time they decide it’s investing day, and then if a refund comes in they spend it. Plus if you figure out later on that an RRSP is better for you, you can easily withdraw from your TFSA and start catching up on your RRSP — if you don’t know any better, the TFSA is a great place to start. Once your TFSA is full, moving on to RRSP next (over non-registered makes sense)**.

Finally, a good related post at Michael James on Money that I couldn’t find a place to link to above.

* – remember that the 31% tax rate is on the pre-tax amount, so the RRSP will have more than $13,100 to invest, but this may come as $13,100 in the first year, then a refund on contributing the refund in a following year, repeating. Or you could fill out the paperwork to get pre-tax money into your RRSP by avoiding tax deductions in the first place.
** – which doesn’t mention the RESP. That depends on your priorities and view towards paying for your kids, but free CESG money is hard to beat so it often goes even ahead of the TFSA.