Why Do Pensions Exist if the Future is Discounted?

December 17th, 2013 by Potato

In today’s post at Michael James on Money, he mentions that we can’t extend generous government pensions to everyone.

Here’s something that I’ve never really understood: how is it that there are so many defined benefit pension plans? The news seems to be full of stories of underfunded pensions (another one today about Canada Post’s), and while I can see the logic that led to underfunding, due to the management of the plan and various incentives, I’m amazed that the plans exist at all. The issue is that people are terrible discounters of the future. I would think it should be easy to convince someone to take a minor increase in pay now over a future pension obligation. I would also think that the individual workers would be worse at that kind of math than the corporations and governments employing them.

Yet pensions exist, so what’s wrong with this thinking?

Perhaps an additional factor to future discounting is uncertainty: having a pension means people don’t need to wade into the dark waters of investing: their future will be taken care of, and that certainty (and service of freeing workers from saving and investing on their own) might trump their over-discounting of future payoffs.

Or maybe the organizations suffer from the discounting more than I had thought. Perhaps the present seems so make-or-break that they figure if they don’t keep current costs low (and thus make expensive future promises), they won’t be around to have to deal with the pension. It could be a dissociation between the organization and those negotiating in the present: the elected officials or car company negotiators figure they won’t be around when the bill comes due, so make some deals that are cheap in the short term.

If the certainty is a large factor in making workers value pensions, that might present an interesting opportunity and psychological approach for helping people think about their future selves and save/invest more on their own.

Wonky Buy vs Rent Calculator

December 11th, 2013 by Potato

One of my shining triumphs here has been to create (with generous help from Matthew Gordon) the ultimate buy-vs-rent calculator tool (direct link to the spreadsheet).

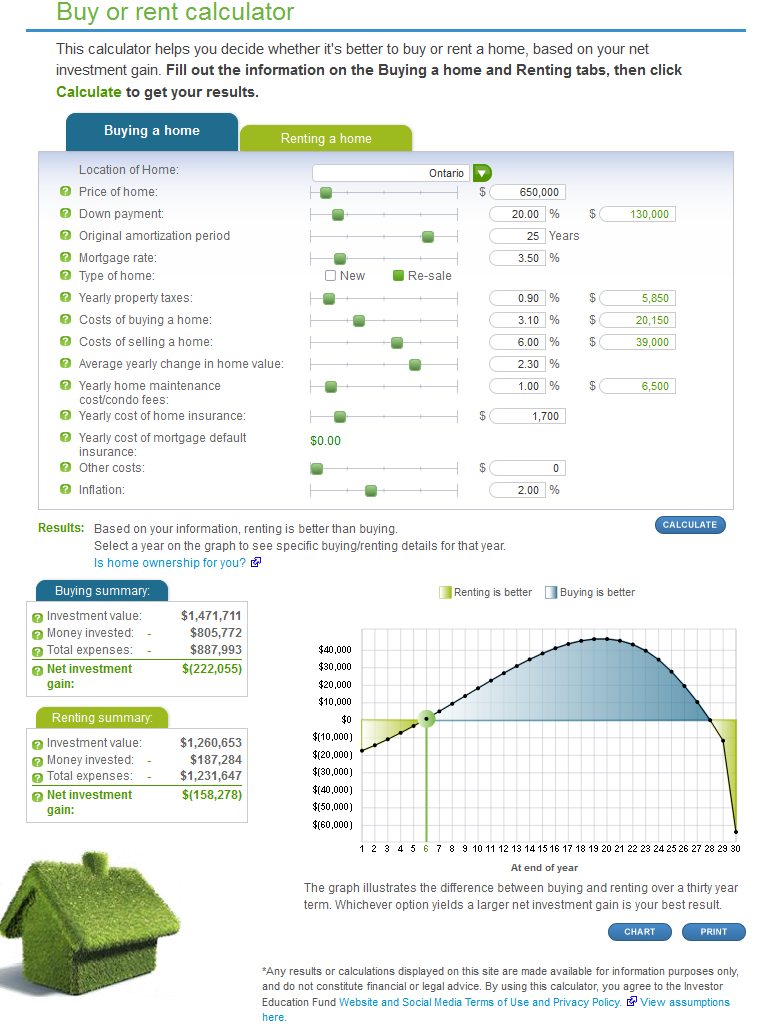
The beautiful thing about a spreadsheet-based calculator like that is that you can follow the calculation, item-by-item, and check it for bugs if you get unexpected results. Earlier this week, B&E posted a list of calculators out on the net, and rather than linking to my supremely excellent calculator and associated post, Robb linked to a Get Smarter About Money calculator. Ok, it’s web-based and a little more user-friendly than a spreadsheet, and has graphs and sliders (though why you need house price to go up to $10M is a question left unanswered)… but was it accurate? I’ve seen many, many terrible buy-vs-rent calculators (even some seemingly excellent ones like the famous New York Times ones that just doesn’t work for Canadians due to tax differences). So I played around with it. And I quickly saw wonky results like this:

Weird behaviour from a buy-vs-rent calculator: the curve simply should not be shaped like that, there's nothing to drive the differences in the last few years. Click to enbiggen.

In the comparison I have there, the price-to-rent multiple is 260X ($2500 monthly rent on a $650,000 house); as we’ve learned from previous posts in realistic scenarios it should be better to rent with prices so detached from rents. Yet here the calculator is showing a rather large benefit to buying if you can only wait 7 years or more. Then, strangely and inexplicably, renting rapidly takes the lead in the final few years of the comparison, with some sort of apparent discontinuity at year 30. If you look at their “chart” you can see more errors immediately: I had entered $2500/mo in rent, which is $30,000 per year, yet the “total renting expenses” came to just $12,360 in their chart, a factor of three too low. The buying expenses were only about $31k in their chart, whereas the mortgage alone is that much, with a total cash outlay of nearly $45k each year.

Now if you instead do the same comparison in my calculator, you’ll find that renting beats buying right from the start (due to the high transaction costs), and is fairly flat in terms of net benefit for about 10 years, at which point the investment portfolio starts to get large enough that investment returns become comparable to rent and the exponential growth becomes truly noticeable. There is no big “buying is better” hump in the middle. Moreover, the magnitude of the difference is notable: in my calculator renting beats buying in such a scenario by over $600,000 in year 30, versus the nearly break-even result from this scenario in the flashy online tool, with the same assumptions regarding investment returns, inflation, mortgage interest, and other sundry costs.

It’s a bit distressing, as other online calculators have recently been found to have serious errors as well. For instance, Michael James uncovered one on the Globe & Mail’s site, and just today news broke on retirehappy about the government’s CPP calculator over-estimating your future CPP benefits and not at all handling early retirement scenarios correctly.

Footnote: let’s say you’re not convinced that my spreadsheet is the gold standard to which all other rent-vs-buy calculators should be held. To then check the accuracy of the online calculator, let’s run the first year’s numbers manually:
Buying: mortgage $31k, property tax $6k, insurance $1.7k, maintenance $6.5k; total cash cost: $45.2k. Principal paid down: $16.5k. Net cost of owning: $28.7k.
Renting: rent $30k, insurance $0.4k; total cash cost: $30.4k. Investment portfolio gains: $10.5k. Net cost of renting: $19.9k. Cost to sell house: $39k. Gain on house: $15k. After year 1, renting ahead by: $49.3k. Online tool says: $16k.
If you notice any errors let me know.

Planning for Aging/Dementia

October 29th, 2013 by Potato

My mom and my aunts were quite concerned with my grandfather’s mental state as he aged. It was becoming clear that he was suffering from the onset of dementia and cognitive impairment (Alzheimer’s specifically), but nobody knew what to do. Most of the time he was fine: dementia isn’t a one-way slide into a mental fog, it’s got its good days and its bad. And living out in the country, just him and my grandmother, driving was an essential part of their lives. Yet clearly ensuring a 3,000 lbs guided missile was always safely operated was a priority for the safety of him and everyone else on the roads. Any discussion of selling the car or turning in his license was a major fight though, with nothing but hurt feelings all around as the girls found themselves up against an immovable object time and again, and not really being sure themselves how essential it was to “ground” him. Then one day while driving he merrily crossed to the other side of the road and sped along, completely oblivious to the fact that he was going the wrong way. Fortunately the lack of traffic on a PEI rural highway meant no one got hurt, and that incident galvanized my aunts and they made him give up his license. Since then, the issue of people being competent to drive has entered more prominently into the national consciousness, and Ontario for one changed its licensing so that seniors had to take regular renewal exams, and made it easier for physicians and family members to report a potentially dangerous driver.

Driving is so contentious because it’s so closely linked with a person’s sense of freedom and mobility; many even view it as a right. Yet it is also visible: you can tell when your parents are uncomfortable heading out at night or in the rain, and you might be in the car when you notice them run a red light, take long enough to get going at a green light that the queue behind them is honking angry, or cross over to drive on the left. Some new technologies like lane keep assist can help improve the margin of safety and keep them driving longer, but you know that one day the decision will have to be made.

Less discussed is what happens to a person’s finances. Even aside from being capable, do they have the interest in rebalancing funds in a passive portfolio? Are all the bills getting paid on time, or are some slipping through the cracks? It’s a much tougher nut to crack: we face significant societal taboos to not discuss finances or mental health, and unlike driving there are no innocent bystanders being run down nor are the problems visible. Also unlike driving, finances can be handled at your own pace, and you can wait until you’re having a good day to deal with them (and for the most complex investing decisions, one day per year may suffice).

Still, the major question is: when should you get help? A DIY approach saves fees and doesn’t require a ton of specialized knowledge, cat-like reflexes, or time invested. The right approach (keeping things simple, following evidence-based best approximations, controlling what you can and letting the market do the rest) can be successful and easy. But it still requires some attention, some decision-making, and some knowledge — and does leave you open for losses if mistakes are made. There will quite likely come a time when some help is needed.

I think a formal, painful process is the way to go. Decide, years in advance while tempers are cool and minds are sharp, what will be the criteria for needing help (family meeting, majority rules? Professional assessment*?). Identify what form that help will take (complete control, advice, double-checking) and who it will come from (relative/friend, professional advisory firm). Perhaps see a lawyer about a conditional power of attorney (IANAL). Yes, it will suck all the fun out of Christmas dinner this year, so maybe combine it with your other painful but necessary family talks that you’ve been putting off (organ donation: take ’em all; life support: trust the EEG and don’t save a vegetable; toilet paper: goes over the top).

While investing seems like the bigger risk — so unfamiliar and rarely encountered — regular monthly bills, credit cards, and chequing accounts can potentially be bigger sources of losses if ignored or mishandled. Systematic withdrawal plans can also simplify and remove execution risk on the investing side (as can automated bill payments on the household management side). Reducing leverage and transitioning to less-active styles are also good ideas (if you used those in the first place).

It’s also a helpful process to go through so you consider what will happen if you die. In that case I think it’s easier** — your non-DIY-investing spouse may need a plan or annuity to help them cope, but at least the situation is a little more cut and dry: you don’t start off arguing about whether or not you’re dead and capable of continuing to manage your affairs, and everyone will know to swoop in and offer to help in that case (and you’ll have a capable executor named to help out, right?).

Not that I’ve actually done any of that with my parents, but I keep meaning to.

* – Note that this is not likely to happen promptly (avoiding the doctor, visiting on a good day, reticence on the part of the clinician to diagnose cognitive impairments)
** – Yes it sounds wrong.

Why Gross Debt Service Ratio

September 21st, 2013 by Potato

I could fairly accurately define a mortgage as a loan that represents the very largest amount of money a person can possibly borrow and still expect to pay back. Though they are thought of as the safest kind of lending, when put in this light you can see that there is the potential for risk: the amounts are large and the timescales long.

If I were to try to create some way of predicting who would be a good credit risk, I would probably look at the household budget: how much money comes in, how much do they spend on what, and from there try to figure out how much that household could afford to put towards their prospective house purchase. Then, I’d have a few thousand potential scenarios with a number of important parameters — periods of unemployment, new children, interest rate changes, stock market returns, inflation in other spending categories, house price returns, etc., etc. — and run some Monte Carlo projections to see how likely this borrower would be to pay me back even if stressed.

That would probably give me a pretty good idea of who I could lend money to. But it is an absolutely ludicrous practice to think about for the real world. Firstly, there is going to be a lot of uncertainty: what if the borrower wanted to defraud me into giving them more money (or “soft fraud” so they could buy more house sooner) and under-stated how much they spent on food, vacations, and Halloween decorations so it looked like they could handle more mortgage than they really could? How would I ever collect and verify all the information they gave me to go into my model? Secondly, I will likely not be the one out vetting prospective borrowers and collecting their information, it will likely be someone who has a high school education (or a liberal arts bachelor degree) who has never heard of a Monte Carlo simulation working in the customer service part of my bank1. My “mortgage specialists” likely couldn’t figure out their own detailed household budget, let alone audit a potential customer’s.

So I want something else that is going to be a pretty good predictor of ability to pay that will also be easy to verify and easy to apply by minimally skilled staff. And when you boil it down there are basically two things that are rather good predictors: how much money you’re making (income) and how much money you already have (down payment).

A larger down payment will mean that you’ll need to borrow less, but it also demonstrates that you have the ability to stick to a budget and save (or relatives who at some point did and liked you enough to give it to you). It gives you “skin in the game” — you’re much less likely to walk away from your house after a 20% downturn in prices if you put 20% of your own money into it. 20% is the cut-off, by the way, below which you must have mortgage insurance for a bank to lend to you

More income means of course that you have more money to pay the monthly bills to service your debt as well as keep the house properly maintained, etc. The question though is what criteria do I set for “more income”? There are many options, so we’ll have to think about what aspects of the problem to consider.

We could simply set a threshold of price-to-income: say you can get a mortgage for 5X your income. So if you had a $50,000 income you could only qualify for a $250,000 mortgage. But a mortgage is so long-lived that the interest rate that applies greatly affects your ability to afford it. At 10%, the mortgage alone would be over half your income, while at 5% it would be just over a third. At 20% it would take everything you had. Interest rates are one aspect to somehow build into our metric then.

So instead of comparing to the total mortgage amount, we could compare to something that more closely mirrored income: the debt service costs — which, if you’ve read ahead, you know is what banks currently do. There are some problems with using debt service costs: because they are interest rate sensitive, you might give out too much money during times of low rates. This was only recently (and only partly2) fixed by introducing the concept of the qualifying rate: your loan is tested against an interest rate of 5.4%, even if you’re able to borrow at 3%.

If we’re using the monthly cost, then we just need to come up with a rough average household budget, figure out how much money can go to the mortgage versus everything else, and we can set up a fairly simple multiple test for our front-line bank staff. But there are some wrinkles to iron out: there’s a big difference between how households split their budget. When I was in grad school, almost 80% of my income went to rent. Food, rent, utilities, and transportation were pretty much the only expenses I had — I was dependent on gifts for clothes and entertainment. Clearly, the average household can’t afford to allocate 80% of their income to housing expenses.

If we look at some hierarchy of needs, shelter is up there, and if you don’t pay your mortgage you could lose your shelter. But it can take 120+ days for the bank to evict you if you skip your mortgage payment, and you’re hungry now. So food expenses, the transportation costs to get to work, and certain addictive vices (smoking, drugs, World of Warcraft) may get paid first. So if we say it takes about 15% of the household budget to cover that, then we can say that debt service costs can occupy the next tier of the budget. But not the entire rest of the budget — we want a household experiencing some stress (perhaps one wage earner out of the work force) to still be able to make those basic needs and service their debt — and an un-stressed household will still have other uses for money (vacations, saving, other discretionary spending), so there has to be headroom there.

Exactly how big that tier should be is a good question and I can’t really answer it from first principles. But the banks and CMHC have come up with 32% for debt servicing and that looks to be roughly in the right range.

Then the next question is what do we use to measure income? After-tax income makes a lot of sense: that is, after all, what you have to actually spend. However, it gets back to our initial problem of trying to make the model too good complex: how do we verify after-tax income? If you’re about to buy a house you might be putting as much as possible into your RRSP, with the intention of using the Home Buyer’s Plan. Those contributions make more of your income tax-free, making your after-tax income look bigger. But will that rate of RRSP contributions continue once you buy the house? What of all the other tax credits and deductions?

Gross income, on the other hand, is fairly easy to verify: an employment contract and/or T4 slip will do it. No fist-fights break out in the bank offices over what should be considered an eligible, sustained deduction, no shoe-boxes full of receipts to dump on the desk. Self-employed people will have trouble with either measure, so forget them for now.

Another advantage of using gross income rather than after-tax income is how it scales: people with higher incomes are able to put more of their budget towards a mortgage if they so choose, because the very basics (food, etc.) are covered by such a small part of what they make, so more of their salary is truly discretionary. They’re also taxed more. If the criteria is 32% of gross income, then someone making $40k and paying an average tax rate of 15% would be able to take on $12.8k/yr of debt servicing costs, and have an after-tax income of $34k to pay that — it works out to 37.6% of their after-tax income. Someone making $200k might have to pay 40% in tax, so their $64k in allowable debt servicing would be 53% of their after-tax income. A fixed ratio of gross income leads to a sliding scale for after-tax income.

Ease of verification, ease of calculation, some prediction of credit risk, and some modest scaling with income actually make the gross debt service ratio a pretty good choice for qualifying people to borrow.

There are still some weaknesses with it, in particular with how interest-rate sensitive it can be. Using a conservative qualifying rate helps mitigate that to a large extent, so I don’t know why there’s a loophole for the most popular kind of mortgage around (5-year fixed). Down payment is a little more straightforward. 20% is, roughly speaking, enough to weather a mild downturn and have enough capital to cover transaction costs if you need to bail. But providing mortgage insurance complicates things: being able to buy with no capital is an accelerating factor for bubbles, and is strongly predictive of default risk[3].

I’ve suggested some simple, easy to apply rules to modulate mortgage insurance: cutting back on the maximum price, scaling back on maximum loan-to-value or increasing the cost of insurance depending on price history, price-to-rent, or affordability metrics could help cool a bubble before it gets dangerously inflated4. However, that would require different rules for different cities depending on local economic conditions, and that doesn’t seem to be politically tenable for the CMHC, even though the rules could be made simple and transparent enough that it would be clear that no particular region was being targeted.

I don’t have a time machine or internal CMHC documents to explain it, but that’s my best guess for why GDS is used as the qualifying metric.

1. In this thought experiment I have a bank. I don’t really have a bank; I don’t even have bank stock.
2. A gaping loophole in the qualifying rate is that you get to side-step it if you lock into a 5 year mortgage (or longer), as most Canadians do. Then you get to use your contracted rate. These loans should also be tested against the qualifying rate for conservatism’s sake.
3. In all the research I’ve done, down payment/equity/LTV appears to be the second-strongest predictor of default after credit score.
4. And provide automatic, measured stimulus in a correction. Lean into the wind to introduce some negative feedback (negative is good).
Of Course You Invest It

September 18th, 2013 by Potato

In almost all of my rent-vs-buy comparisons I have the renters invest their capital and ongoing savings, including in my most recent one about the three year condo holding (Toronto Condos: Best Case Scenario). Note that the renters didn’t have to in that scenario: the buyers lost so much to frictional costs1 and higher ongoing costs2 in their short foray into condo life that the renters could have left their cash in a chequing account and still come out ahead. But I had them invest it anyway because that is what you’re supposed to do. It didn’t hurt that doing so helped hammer the point home, making the spread in outcomes so large that you could be especially generous to the buying case (e.g. assume they were prescient about their mortgage needs rather than acting like a typical buyer) and still conclude that renting for 3 years is hardly throwing your money away — it’s the opposite. But that’s not why I chose to: it’s my default recommendation and assumption.


On Twitter, @barrychoi questioned the assumption that the renters would invest their capital. I wondered why you wouldn’t, to which he replied: “for time purposes. Is it worth risking your money if you might need that cash soon?”

Here is the thing, “need” and “soon” mean different things when you’re talking about housing. There are a lot of rules of thumb out there, but the general idea is that equities are volatile, while providing high return expectations. So you should invest money for the long term in equities, but not money you might need in the short term because you could be hit with a market down-turn just as you’re about to take your money out and spend it. The rules of thumb say money you need in about 5 years, or 10 if you’re really conservative, should be in something safer.

This is trying to take a heuristic shortcut to risk tolerance, but risk tolerance is made up of many components. The ability to recover is a big part of it, and it’s closely related to the time you have on your hands, which is where these rules of thumb are derived from. They’re also influenced by the history of the stock market and how long it may take to recover from a typical crash. If your timeline is too short, you could get unlucky and be caught in a crash just as you need your money, and have to eat the loss.

But when you’re talking about buying a house your timeline is not generally short: in the example David Fleming provided that inspired the previous blog post, the couple had been in a condo for ~3 years, and was looking to rent a slightly larger condo for another year or two before buying. Close enough to the 5-year rule of thumb to go investing the capital. In general, at the very least you’ll be signing a lease for a year, with a likelihood of renewing and maybe even having another rental stage before ending in your “forever house.”

Even if you’re not a housing bear3 and are just renting for a few years to avoid the ruinous transaction fees or until your career settles down enough that you have some certainty you won’t be packing your bags for the other side of the continent, you’re going to have a few years to play with. Just because the rule-of-thumb is 5 years doesn’t mean you’re insane to invest with a planned 3 ahead of you. Because if you are unlucky, you don’t need to buy a house on August 15th, 2016 like your plan says — you won’t vanish into a cloud of pixie dust and parental disappointment if you still have a lease on Tuesday — you can chill and rent for a few more years if you need to. Plans can be fluid that way, and that kind of flexibility is what gives you the risk tolerance to invest in equities.

Your plans are not set in stone, and the ability to defer your purchase date adds to your risk tolerance.

Aside from not needing to buy on a certain date, you don’t need a specific, immutable downpayment. If you invest a $100k nest egg, you expect that, with a 6% return, you’ll have $126k after 4 years when it might be time to buy. It could be better than that4, or it could be worse; uncertainty is something to deal with rather than fear. If you are unlucky and in four year’s time there is a terrible correction and you’re down 25%, well, you just lost $25k and it stings, but it’s not going to ruin your life. You take the reasoned gamble that you’re more likely to be up money by investing in equities for the next few years — and that, in advance, you’re not sure whether “next few years” will turn out to be 3 or 10. In many scenarios you will be proven right and be better off. But even if you do lose that bet, it’s not like you can’t buy a house at all, you just have to settle for less house or more leverage. Your original $100k (plus accumulated savings) might be enough for 20% down on a $500k place, but if you come to the table with only $75k you can still buy a house — with CMHC you can even still buy the $500k one from your twentysomething dreams. The risk to your life plans is not that large: it’s not a life-altering risk you’re taking, but a manageable financial one.

If you’re a housing bear like me and have recognized that with crazy price-to-rent metrics it just makes more sense to rent, then you’ll be doing so for as long as it takes. Housing corrections take years to play out. And a housing bust is almost never a “V-shaped” event, where you only have a few weeks or months to swoop in on cheap prices: once the excess comes out (which itself will be a multi-year correction event even in a crash with numerous accelerating factors like in the US), the market will very likely stay in “fair value” range for a few years. As a bear you may be living in a rental house that would sell for5 $500k in today’s bubbly climate. One day, if prices make sense, you might like to own a similar house, but it’s 30% over-valued. So you rent, invest, and get on with your life. But if the conditions have changed so that it’s time to buy then that house has likely come down over $100k in price — you’d still be way ahead even if you were unlucky in equities and lost $25k of your downpayment. And, if you want, you can keep renting for another few years to see if equities recover, knowing the house likely won’t. And conditions might not change: in which case your “downpayment” fund is really your “retirement fund” in a soft-landing world for renters.

Of course you invest it if you’re a housing bear.

So when you’re talking housing, you generally have some long timescales to play with. Maybe not the 10+ years needed for the chance of a negative outcome to go to nearly zero, but enough that investing in equities is not some wild, undisciplined gamble. Even a 3-year holding period has something like an 80% chance of beating cash. I think too many people are too afraid of uncertainty, particularly young people who have a lot of ways to recover from loss at their disposal6. Risk tolerance comes from many sources: you can be flexible with your timelines if needed, or adjust your expectations/budget. And you need a downpayment, not the downpayment you started with — ending up unlucky and losing a portion of your downpayment is generally a survivable event.

My dad taught me at a young age that you only put in the stock market what you can afford to lose. But the market doesn’t go to zero even in a bad crash, and the amount you can afford to lose is generally not zero even when you’re house-horny. So with that in mind I take acceptable risks to try to invest my money in a way that maximizes my expected value.

Plus I know that the risk I’m taking as a renter with equity investments is way smaller than the risk a buyer in today’s market is taking (both financially as well as to my future lifestyle and mobility options).

1: Realtor commissions, CMHC premiums, mortgage break fees, and possibly land transfer taxes (or the burning the opportunity to use the first-time buyer exemption later on a more expensive property), legal fees, inspections, and the inevitable over-spend on customizing (or as is often the case for new condos, finishing the job the developer botched).
2: The higher monthly costs to own (condo fees, interest, property tax, etc) that add up to more than rent, a renter can save in this market.
3: Why are you not a housing bear? Have you seen my spreadsheets? You must live in Hamilton… or non-waterfront Gravenhurst.
4: Indeed, I was more confident being fully invested in 2009/2010 coming out of a huge crash — with the valuations and recovery it seemed unlikely that a second major crash would take us yet lower. If, as in the previous example, someone had listened to me then but with $100k they’d have hit the $125k mark in just three years. Also, I’ll add down here in the footnotes that if you’re close to the CMHC threshold then the potential gain of going over the 20% mark might provide an added incentive — though the downside is there as well.
5: I refuse to say “worth”.
6: Again those are dodge, dive, duck, dip, and dodge… er… Wait, it’s: defer, earn, save, change expectations, leverage, and run crying to mommy.