Group Deals Passe

March 21st, 2012 by Potato

Well, it looks like the group deal fad may finally be getting to its final phase. About two years ago new group deal sites were popping up like crazy, offering steep discounts on everything from restaurants to meat to rock climbing.

I quickly soured on the concept after finding a few deals hard to redeem (one $10 offer ended up expiring before I could use it, and it ended up being a real last-minute rush to finally use my rock climbing pass the week before it expired). Some people got burned bad by the various butcher offers. Plus after the first few months there didn’t seem to be any decent deals, and far too many individual deal sites to track. I ended up signing up for Red Flag Deals’ roundup, which monitored most of the deals and just sent you one email… and really, there’s been nothing to get me excited. Many recent deals have you paying for coupons, which is confusing and stupid.

Then recently I noticed large discounts starting to come back, such as today’s wireless iphone keyboard for 60% off ($50 normally $120!!). Except… that’s not the regular price, or at least it shouldn’t be. Futureshop has it at $90, and Amazon (US) as cheap as $19. Plus the small print in the email says you have to pay for shipping as well, making that a paltry 30% off the futureshop price. There are plenty of other examples, so be sure to check if the huge percentage off advertised by the group deal is actually what you’ll be saving: it may not be worth the hassle if the so-called discount isn’t remotely realistic.

BMO Mortgage Special

March 17th, 2012 by Potato

I’ve been scratching my head about the BMO special since the first iteration in January.

It’s puzzling because it seems so unprecedented: I can’t recall the banks openly competing on price this much before. I can think of a few reasons for it, but those don’t give me much comfort in the motives:

1. BMO is willing to trade margin for marketshare. This could work long-term for them, since many of these customers will renew in 5 years with BMO at higher spreads, but aggressive banks aren’t comforting. There’s a reason we like to comfort ourselves with the image of the conservative Canadian bank. There are news reports that BMO has been losing market share, which could explain this push to take it back, but desperation is no better a trait than aggression in a bank.

2. It’s about funnelling people into fixed rates. The 2.99% special is a lower rate than their (posted) variable-rate mortgage, and only a few basis points above a discounted variable. Maybe they saw something they didn’t like about Canadians’ abilities to handle future rate increases on variables, and BMO is trying to stabilize the portfolio at the expense of margins and shaking up the market. On the one hand, that could be seen as being relatively comforting: distressing that they got worried, but comforting that they’re taking steps to mitigate risk to rate changes. On the other hand, the fixed rate funnel also means that they have now lowered the qualifying rate from ~5.5% to ~3%, and if they needed to take that step to get people to qualify, I quake in fear. OTOH, the 25-year amortization suggests they’re not trying to scrape the bottom of the barrel.

3. It’s about the lack of features. Combined with #1 (adding business down the road), the lack of prepayment means people won’t take as much advantage of the low rates to pay down principal, so upon renewal they’ll get a larger mortgage (or more certainty of that larger mortgage) at the new rate.

On a systematic level, I don’t know what to make of this policy. It could help stabilize the housing market, or contribute to the last hurrah of getting marginal buyers in. For BMO, it could be a shrewd long-term move, or an act of discounting desperation. It’s a puzzler.

Things Are Getting Very Real

March 14th, 2012 by Potato

We’re clearly doing this all wrong. While we’re getting prepared and things are starting to feel very real now with all the baby stuff, we’re not spending nearly enough time enjoying our last kid-free days. I think that delightful mixture of anticipation and terror is giving way to thoughts of “what have we done” and brief panic attacks. But we’ve done our first aid and baby care and birthing classes; the furniture is assembled and the adorable baby clothes ready to be puked and pooped on. I don’t know if anyone is ever fully ready for this, but we’re as close as we’re going to get.

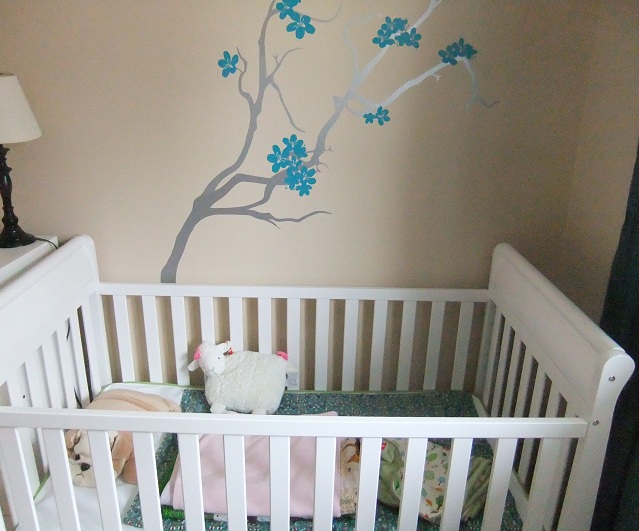
And most importantly, the nest is feathered:

The crib is assembled and the wall decals up.

[And no, the stuff in the crib won’t still be in there when it’s time for baby to go in, we’ve been warned about suffocation hazards. But for now it’s adorable.]

Tater’s Takes – Charlie Munger

March 8th, 2012 by Potato

I still can’t believe how busy I am in unemployment. I figured if nothing else, having no steady income would be a chance to take some time to catch up on all the video games I didn’t play over the xmas break. Instead, I think I’ve been almost as busy as when I was working. The move didn’t help with that, so once I finish the last bit of unpacking (this week?) that might give me a bit of time back (and none too soon — Mass Effect 3 just came out!).

What I’ve found really shocking though is the complete silence on the job front. Not a single interview, even for the jobs I was perfect for. Ah, well, hopefully something will come up soon… On with the links!

An old speech of Charlie Munger’s is reposted, and it’s still good reading.

Rick Mercer epitomizes the condo insanity with the Condo Gun.

More and more housing bubble stories in the media, including the cover at Maclean’s. VREAA says this:

“Show of hands.. Anybody who hasn’t heard that Housing in Canada is in a ‘Bubble’?
Nobody?
Okay… so we’ve all heard.
Pumps are primed.
Now class… How are we going to respond to initial price drops?
Anybody?”

Larry MacDonald puts up another blog post attempting to counter the housing bear sentiment. I will admit: I simply do not understand his position. He doesn’t seem to refute the severe overvaluation — indeed, he confirms it — yet for some reason it doesn’t seem to bother him. Instead he talks about the lack of catalysts: “I agree with him that there is over-valuation—but I also believe there are other factors to consider. […]the catalyst for an end to the U.S. housing mania—a major tightening in monetary policy. I don’t see it in Canada yet;[…]” [emphasis mine]. To put it in terms of a bad analogy, it’d be like being at a party and finding a gas leak. “I smell gas. This is dangerous, I’m getting out of here” I’d say. “I smell it too,” Larry might say, “but nobody’s smoking in here. It’s fine. we can just open the windows and it’ll slowly air out.” “Well, either it blows up, or we’ll feel a chill with the windows open. Either way, this party is going to suck. Later!”

After saying he was leaving blogging and posting less frequently, TMW returns with this little post on valuing real estate. What I find hilarious is that just a week or two ago the BoC released a report saying that this was exactly the algorithm people used when valuing real estate, and that it was faulty because all it did was check to see if a particular property was over/under-priced relative to recent market moves, but implicitly assumed that both the starting price and the growth rate were rationally determined by an efficient market. If those two conditions weren’t true — and believe me, they’re not — then bubbles easily form because very few market participants are doing absolute pricing analysis. So this is a great method to use if you want to try to price a property for sale (to meet current market conditions), and a good one to use if you don’t care about overall valuation and just want to avoid being the one sucker who buys the most over-priced condo in the building… but you need an additional check as to the overall market sanity (i.e.: a rent vs buy analysis for your situation).

John Hempton at Bronte Capital explains why, despite Bronte’s small size, he isn’t chasing small caps. In short, he doesn’t think they’re as over-looked as many who chase small-caps think.

Boomer & Echo compare index funds to the big bank’s equity mutual funds. It goes about as well as you’d expect.

Michael James wonders if Berkshire Hathaway may be an index alternative and suitable for a passive investor. I figure why not: it’s diversified, the fees are low, and the long-term track record is good.

An article in the New York Times describes research that shows people with high IQs may get better investment returns. Though it doesn’t look like the returns come from digging up under-valued stocks, simply from following common sense investing principles that don’t require a high IQ to understand. “[Economists…] argued in a paper published in 2008 that many households avoid investing directly in stocks out of vague fears that they might be deliberately misled or cheated.” I know I’ve seen that kind of misplaced distrust many times when discussing investing. Somehow, over-valued under-diversified real estate is safe, and stocks are a rigged game.

Teller talks about magic and human perception. A fun little read! [HT: Barry Ritholtz]

The Deceptive Importance of Changes in the Homeownership Rate

March 2nd, 2012 by Potato

One meme out there regarding the housing bubble is that today’s price doesn’t matter because immigrants are going to create so much demand that they’ll support the market. “Toronto has X thousand immigrants. Every year.” To paraphrase & combine a few examples. Thing is, you can’t look at immigration in a vacuum. Ben Rabidoux must be seeing the same chatter, since he also just had a post on population growth.

Consider my shower. Let’s say I just bought the AwesomeSauceâ„¢ 8-head shower system, capable of spraying out an amazing 23 litres of skin-scorching hot water a minute. I clamber on in there, intent on scrubbing away the shame of being a renter.

How long before I flood my house?

You can’t answer because that’s just one part of the problem, on the other side is my drain, taking away the influx.

So for immigration, part of that is just offsetting the natural population decline in the country. The net national growth rate is just a touch over 1%. It’s higher in Toronto and Vancouver, but still just about 2%. For comparison, the US growth rate is about 0.8%, and was running neck-and-neck with Canada over the last decade. Ben has some charts showing how much higher it was in some states that boomed and busted.

Ok, 2% growth per year every year is a fair bit of growth: enough to over-power infrastructure and public transit and the like over time. Toronto is full and getting even more crowded. But is that demand driving housing prices, and will it continue to drive housing prices? How can we consider other metrics in the face of the unstoppable immigration tidal wave?

Another important factor to consider is the ownership rate: in 10 years we went from something like a 65% ownership rate to 70% nationally. That seems like a trivial change: half a percent a year. Let’s try to put that ownership rate change in perspective with population growth to get an idea of some of the trends driving housing:

In the GTA, with all that immigration, we went from 5 million people to 6 million in 10 years. That’s something like 650k-700k new owners created by immigration/population growth (households would be lower by some factor like 2.4X, and about 300k of the newcomers would be renters). We also created 250-300k new owners by increasing the ownership rate. And that’s if you are conservative and assume that the increase in the ownership rate in a boom town is the same as it is nationally.

To get to my point: there’s a limit to how much that ownership rate can be increased. There’s a hard limit of 100%, but even below that, there will be some portion of the population that just isn’t going to buy. Even if we don’t reverse course and bring it back down to 65% — just stay here at 70% — that has consequences. Over the last 10 years, demand has been 40% higher than it “should” have been because of the expanding ownership proportion. We had ~1M (or likely more) new owners in the GTA rather than ~700k expected from population growth alone. If the next 10 years features a reversal of that trend — owners becoming renters again, or the average age of owning pushing back a few years — then demand could swing from 1M/decade to 400k/decade, or a 60% drop. Even just stopping the process of borrowing future demand and hitting a plateau represents a 30% decline in demand from the current run rate.

What will that do to prices? To be fair to my point above about looking at both sides, you have to know what the supply situation will be like. But everything suggests supply will stay robust.

Unfortunately like many other pieces of the puzzle, there’s no timing information with this one: though the US topped out at 70% homeownership, that’s not to say that Canada can’t keep going for 75% in the next decade, or 80% in the one after that. But the seemingly small change in this number represents a very meaningful slice of demand, so it’s important to understand — doubly so because it’s a factor that has changed over time, whereas population growth and immigration have been steady for much more than just the last 10 years.